Latest from BCA Research

The dollar’s pullback masks a quiet improvement in its cyclical backdrop, with growth, monetary policy, and flows turning in its favor. As markets fully price out geopolitical risk, the USD should decouple from oil and better reflect these gains, despite lingering structural headwinds.

Hungary’s growth outlook has improved as the election of a new government will likely unlock significant EU funds for the country. Currency traders should go long the Hungarian forint / short US dollar.
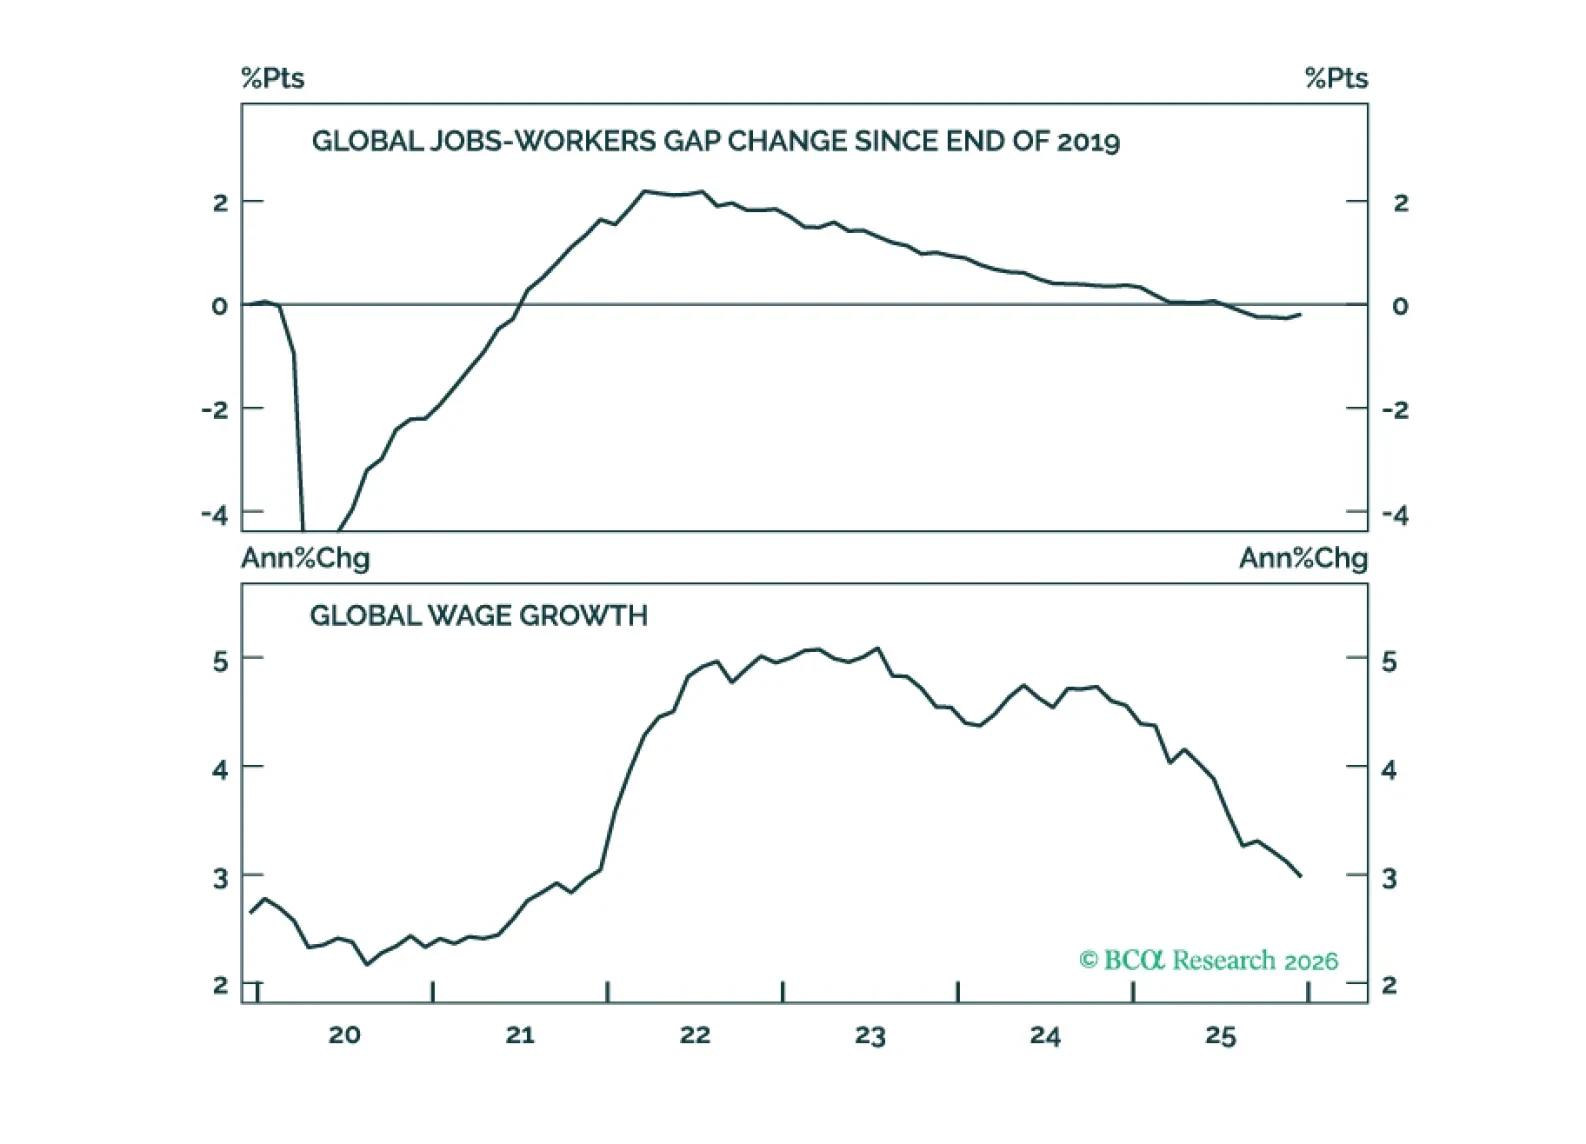
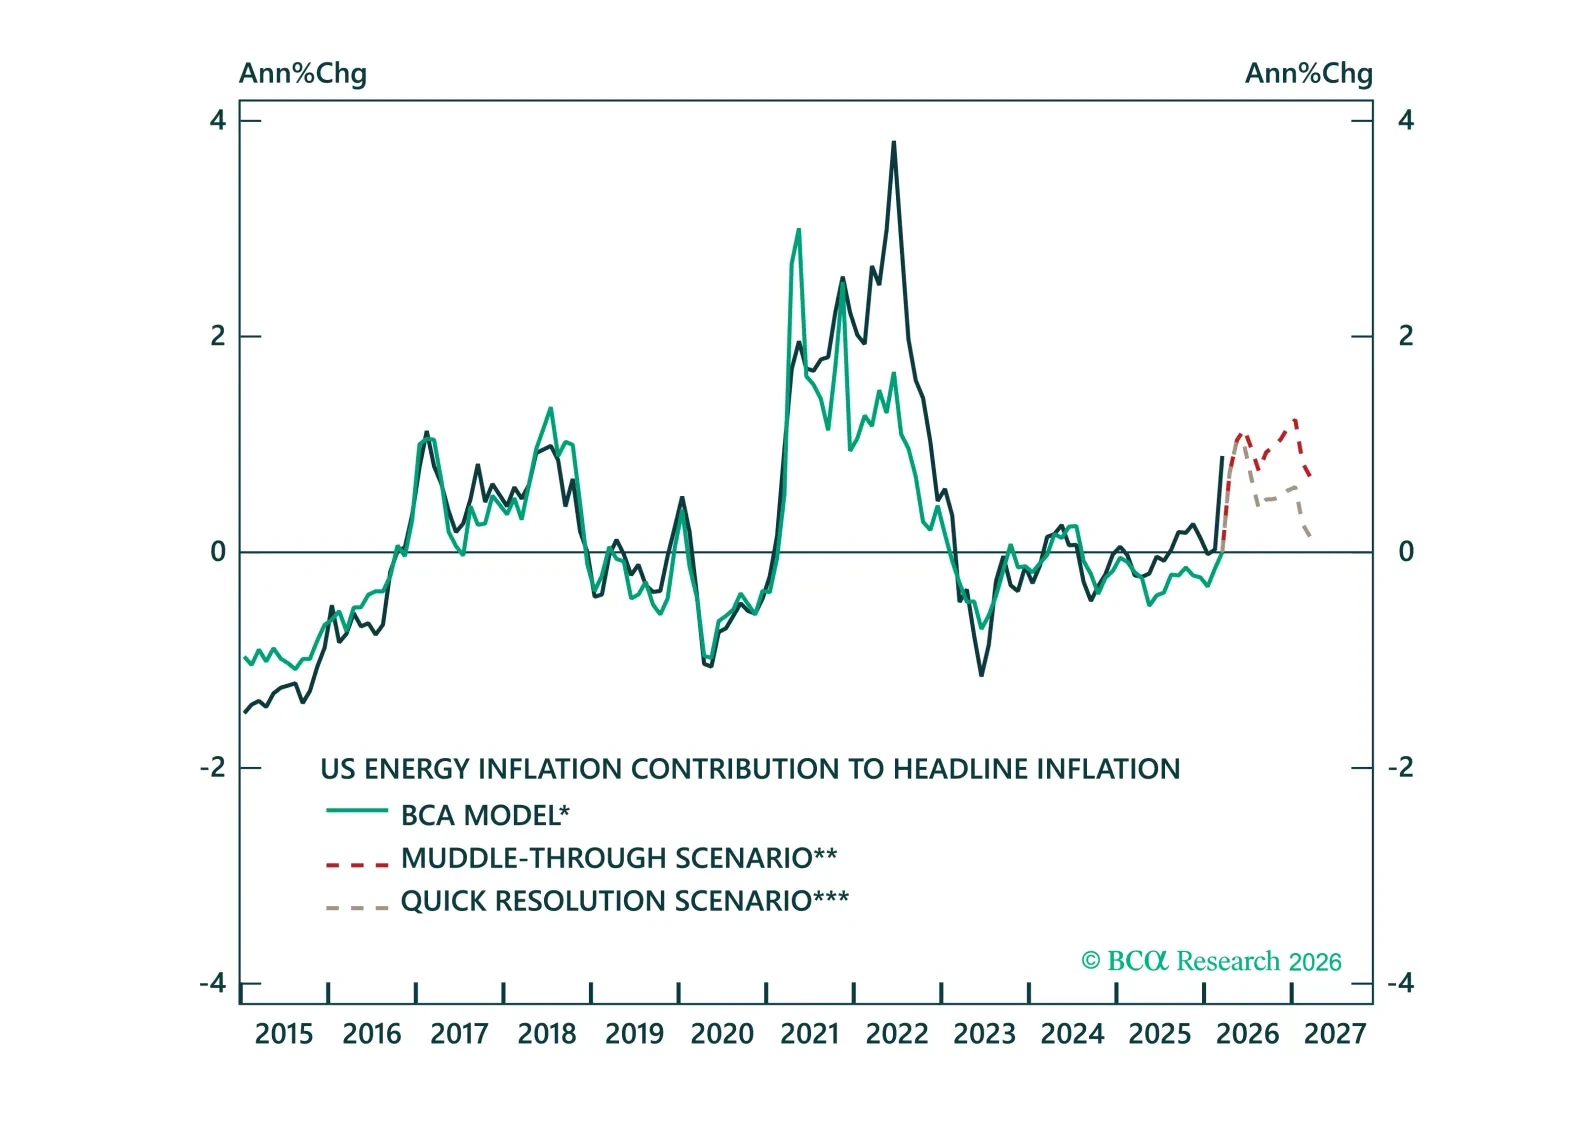
We do not expect the oil shock to have a lasting effect on inflation. Looking further out, a variety of structural forces will influence inflation, including fiscal policy, globalization, demographics, and AI.
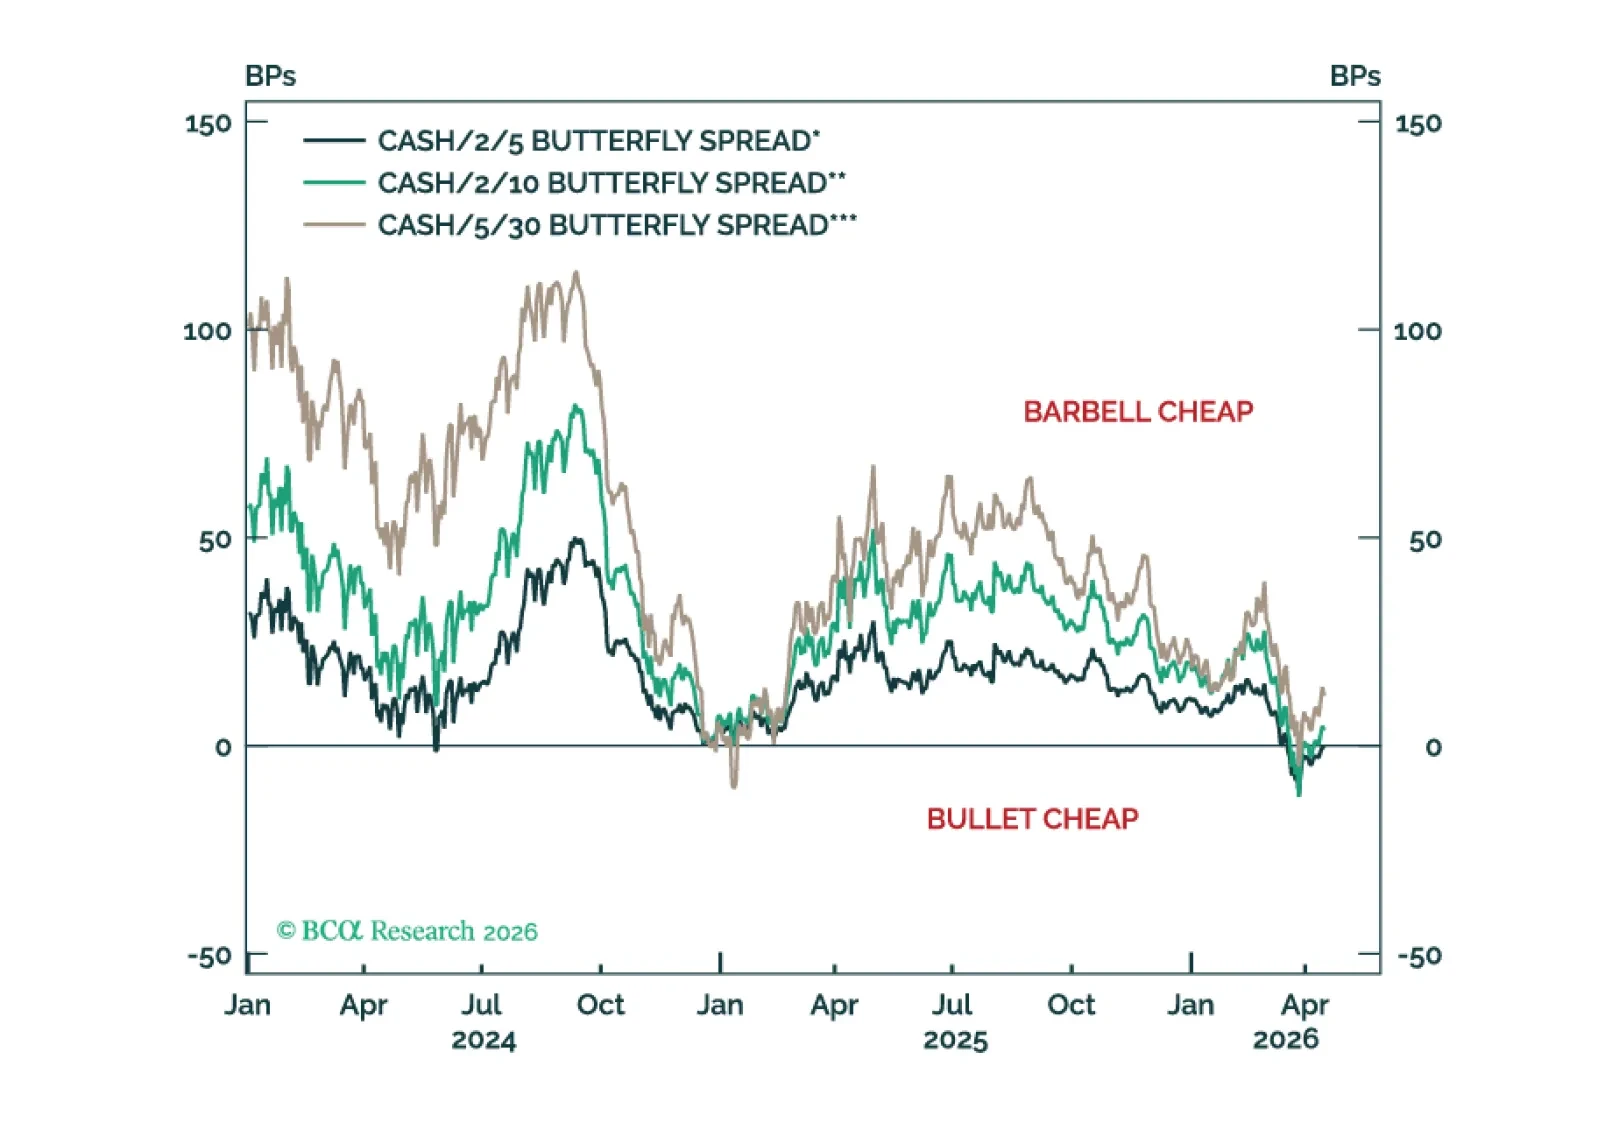
The rates market is moving back into a low vol regime, but with yields at a higher level. This argues for maximizing carry across the Treasury curve.
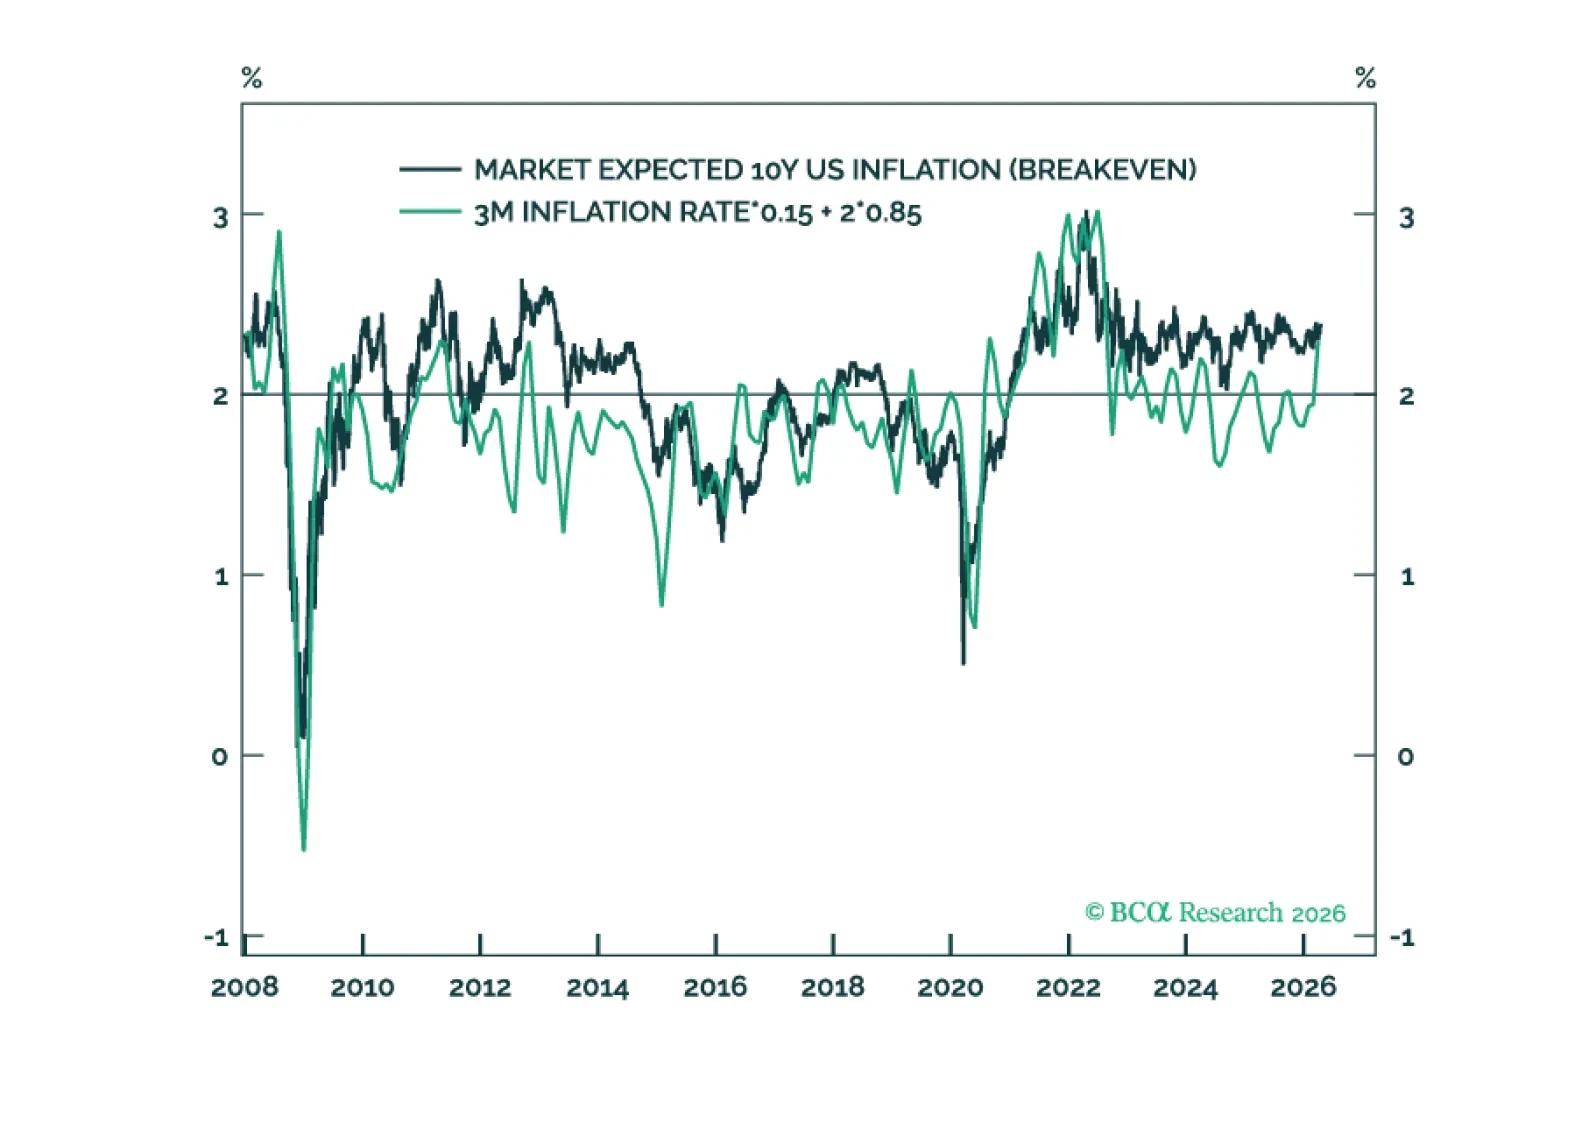
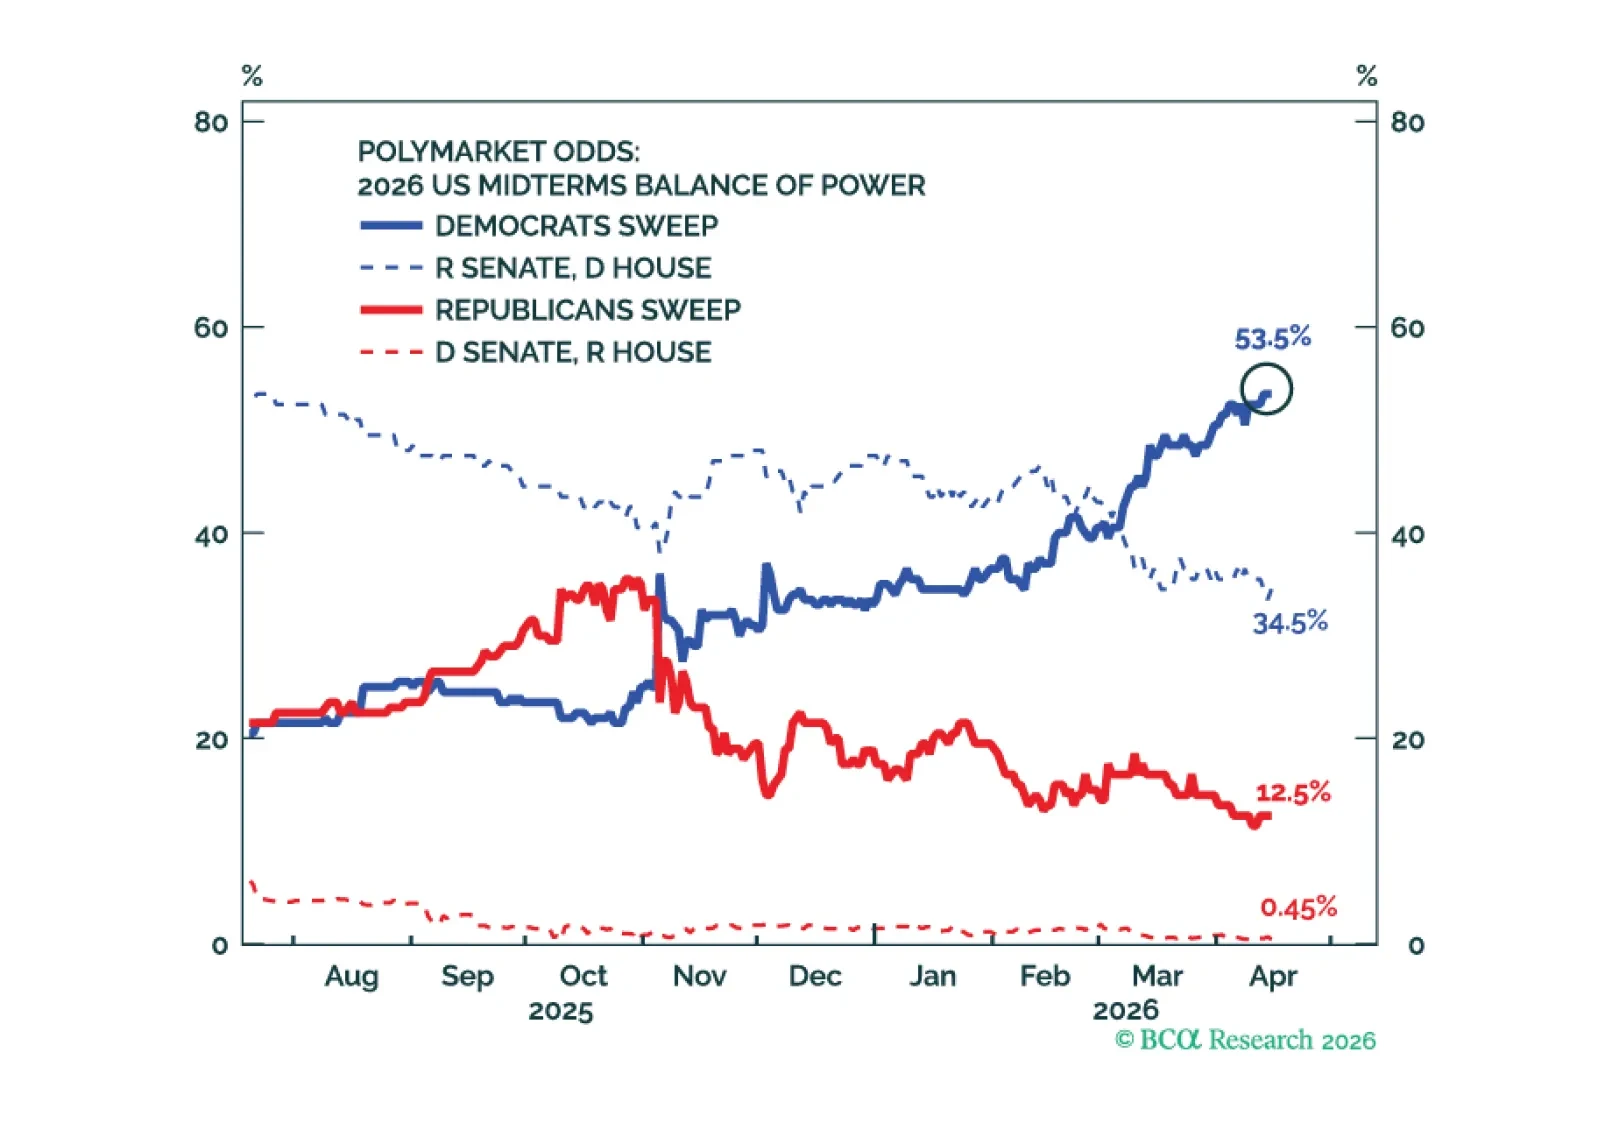
Markets may be underpricing a bifurcated political outcome. Unless the Iran deescalation succeeds, the delayed economic fallout from the energy shock could materially worsen Republican prospects and raise the probability of a Democratic Senate victory.
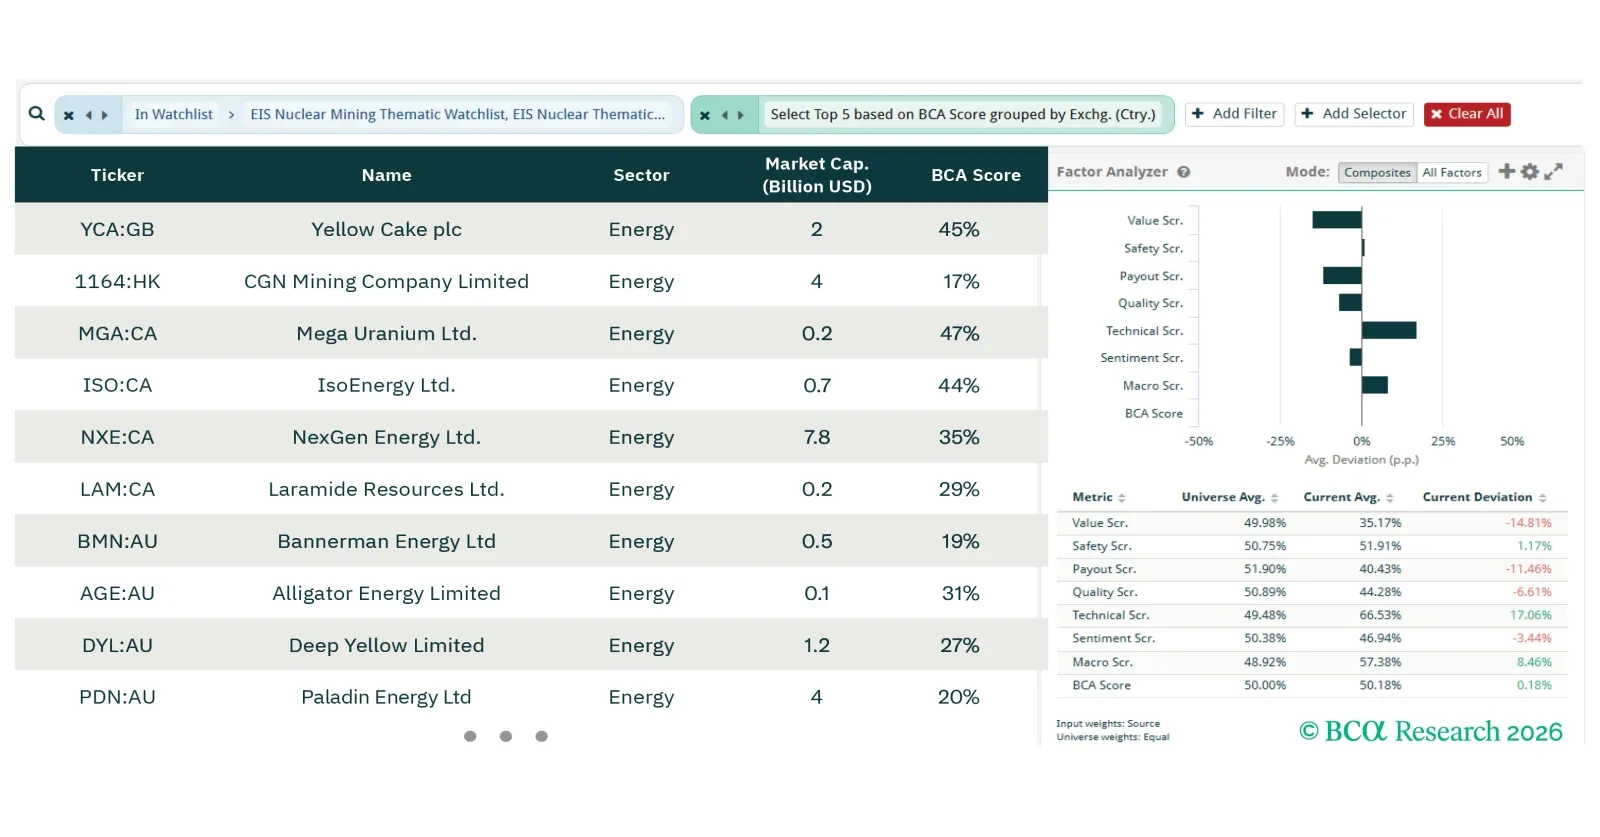
In this screener report, we explore opportunities in nuclear theme, geopolitical hedge, and winners from AI productivity boom.
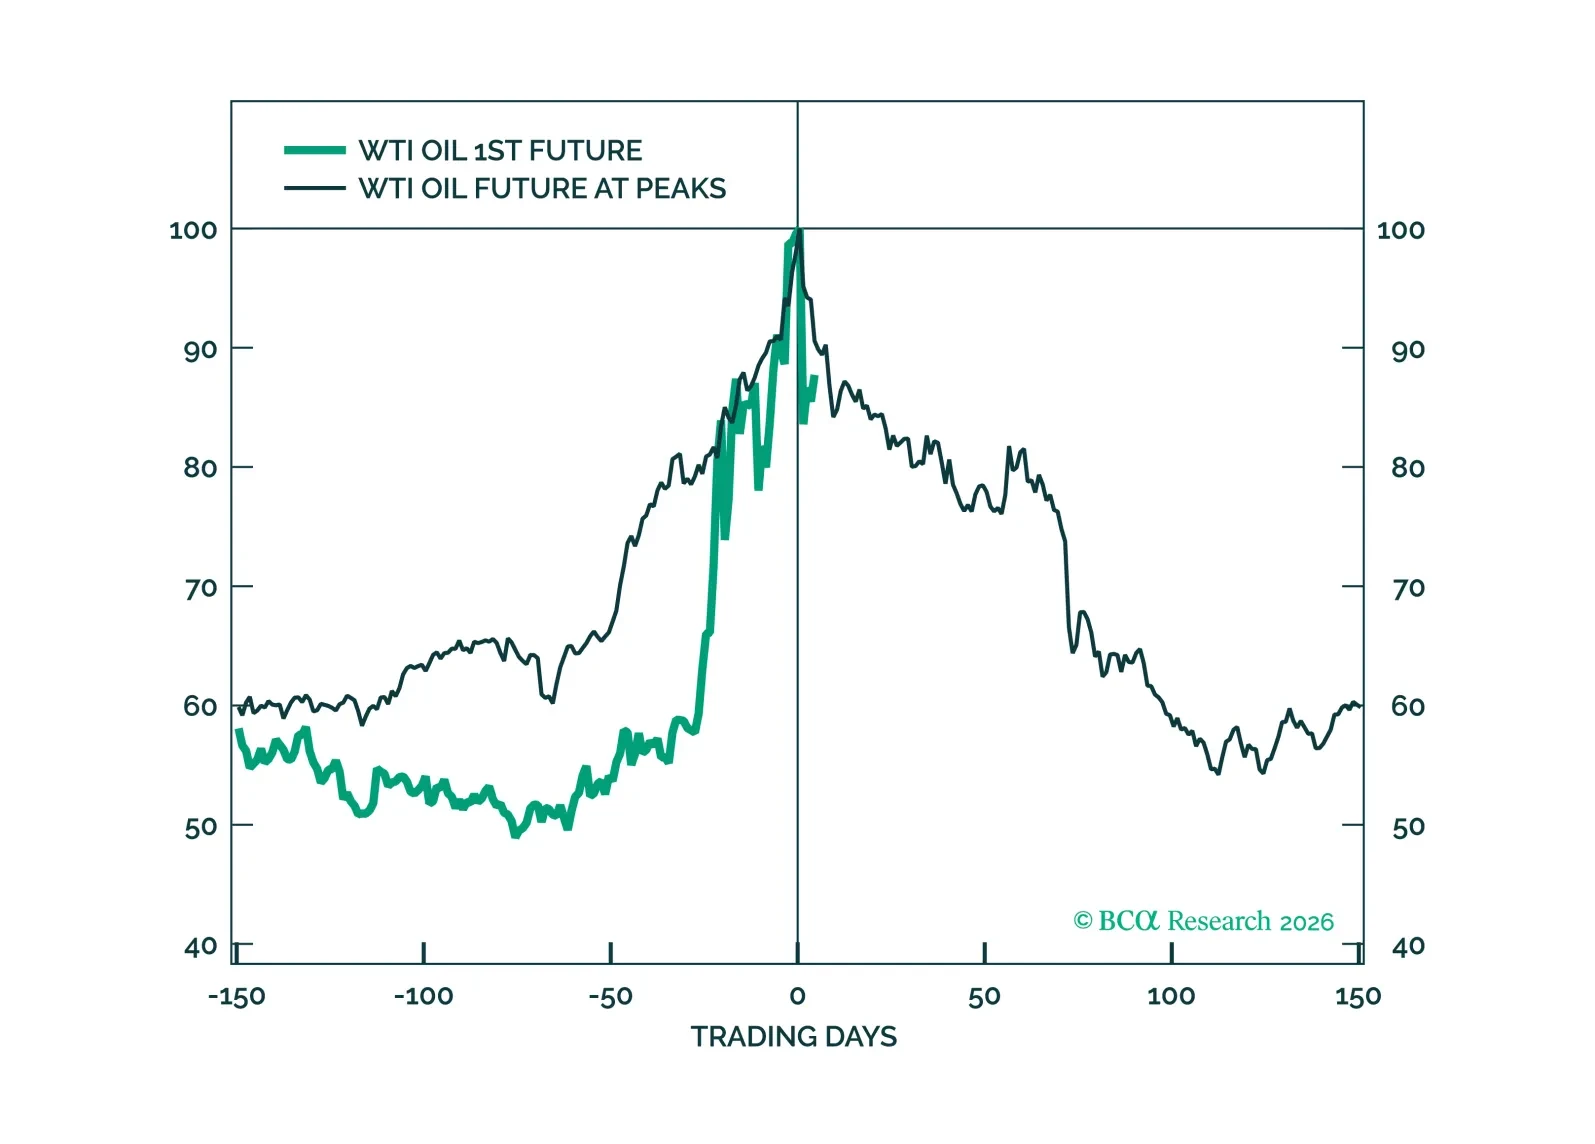
In this chartpack, we present the logic behind our sanguine view and why we think that oil has peaked. We also elucidate our three main scenarios from here on out.

The main reason the oil shock has not caused stocks to crash is that investors do not expect the shock to last very long.
Volatility is high, but the path for yields is clearer than it looks. Across three oil scenarios, we show how policy responses shape fixed income markets and why the balance of risks still points to lower yields.