Latest from BCA Research
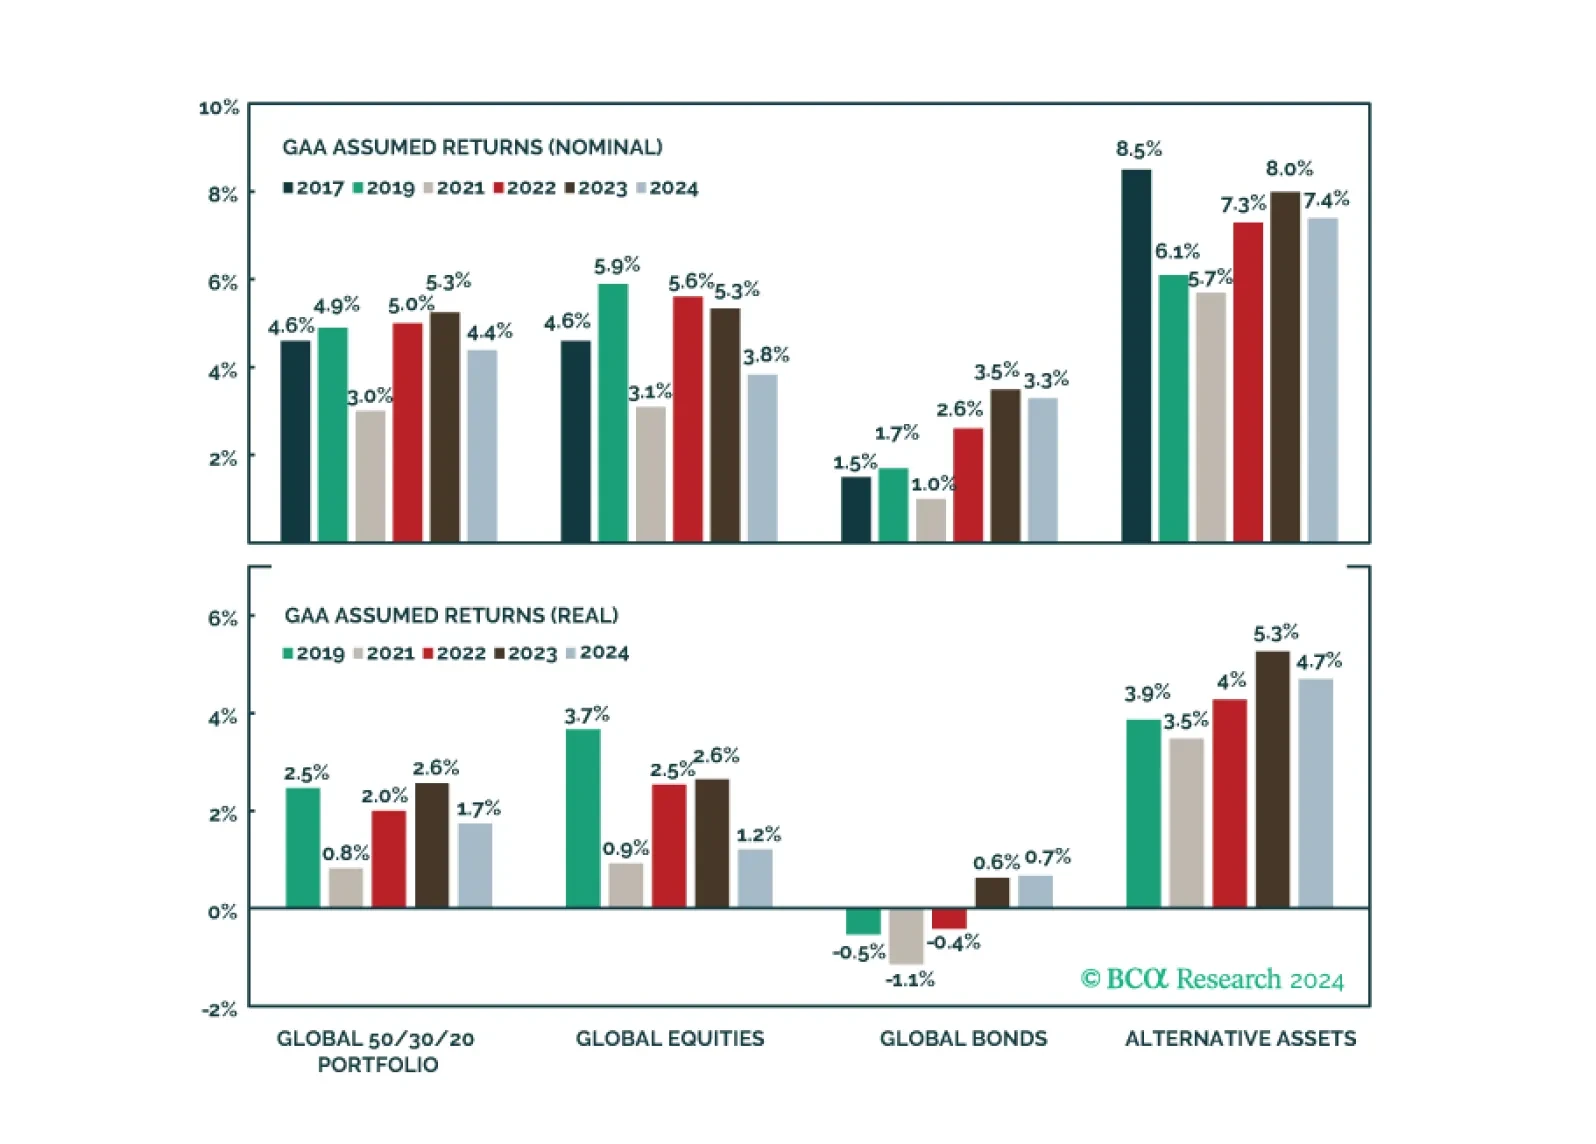
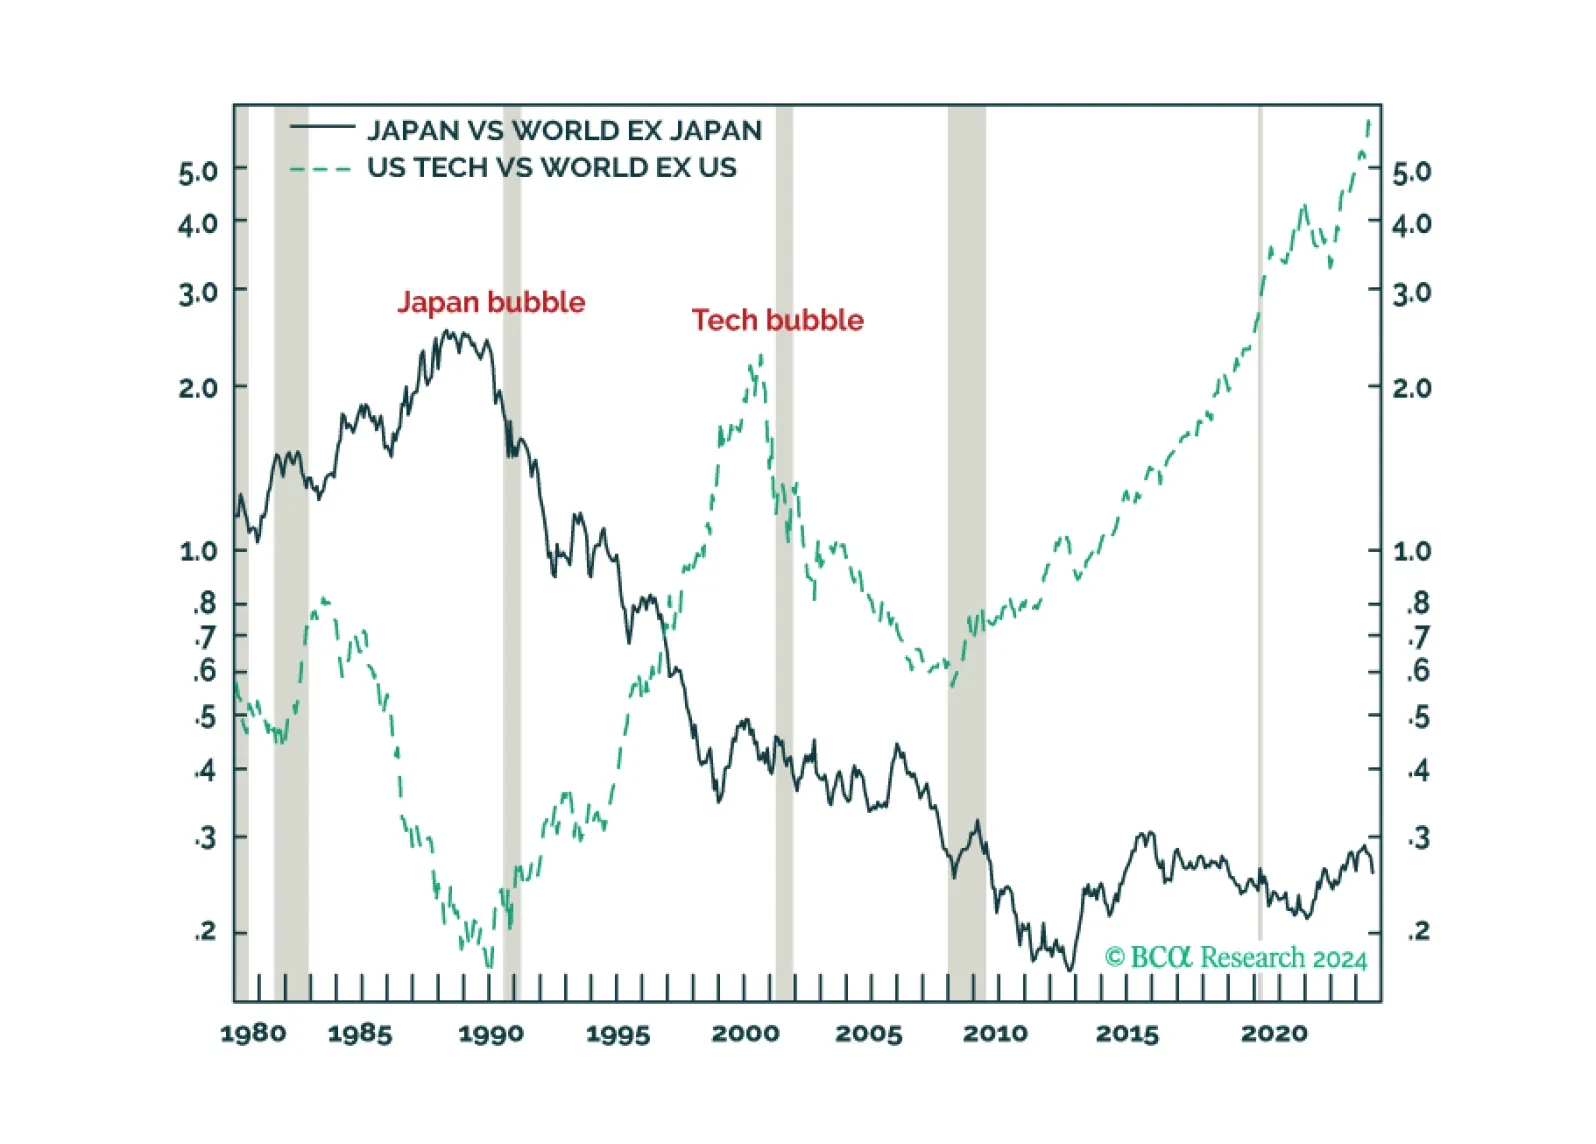
Investors should worry much less about a US or global recession than they should worry about the bubble in anything AI-related. This means staying overweight bonds and the JPY, underweight US tech and quasi-tech, and underweight the US. Plus: SGD/USD is vulnerable to reversal, while copper versus gold can rebound.
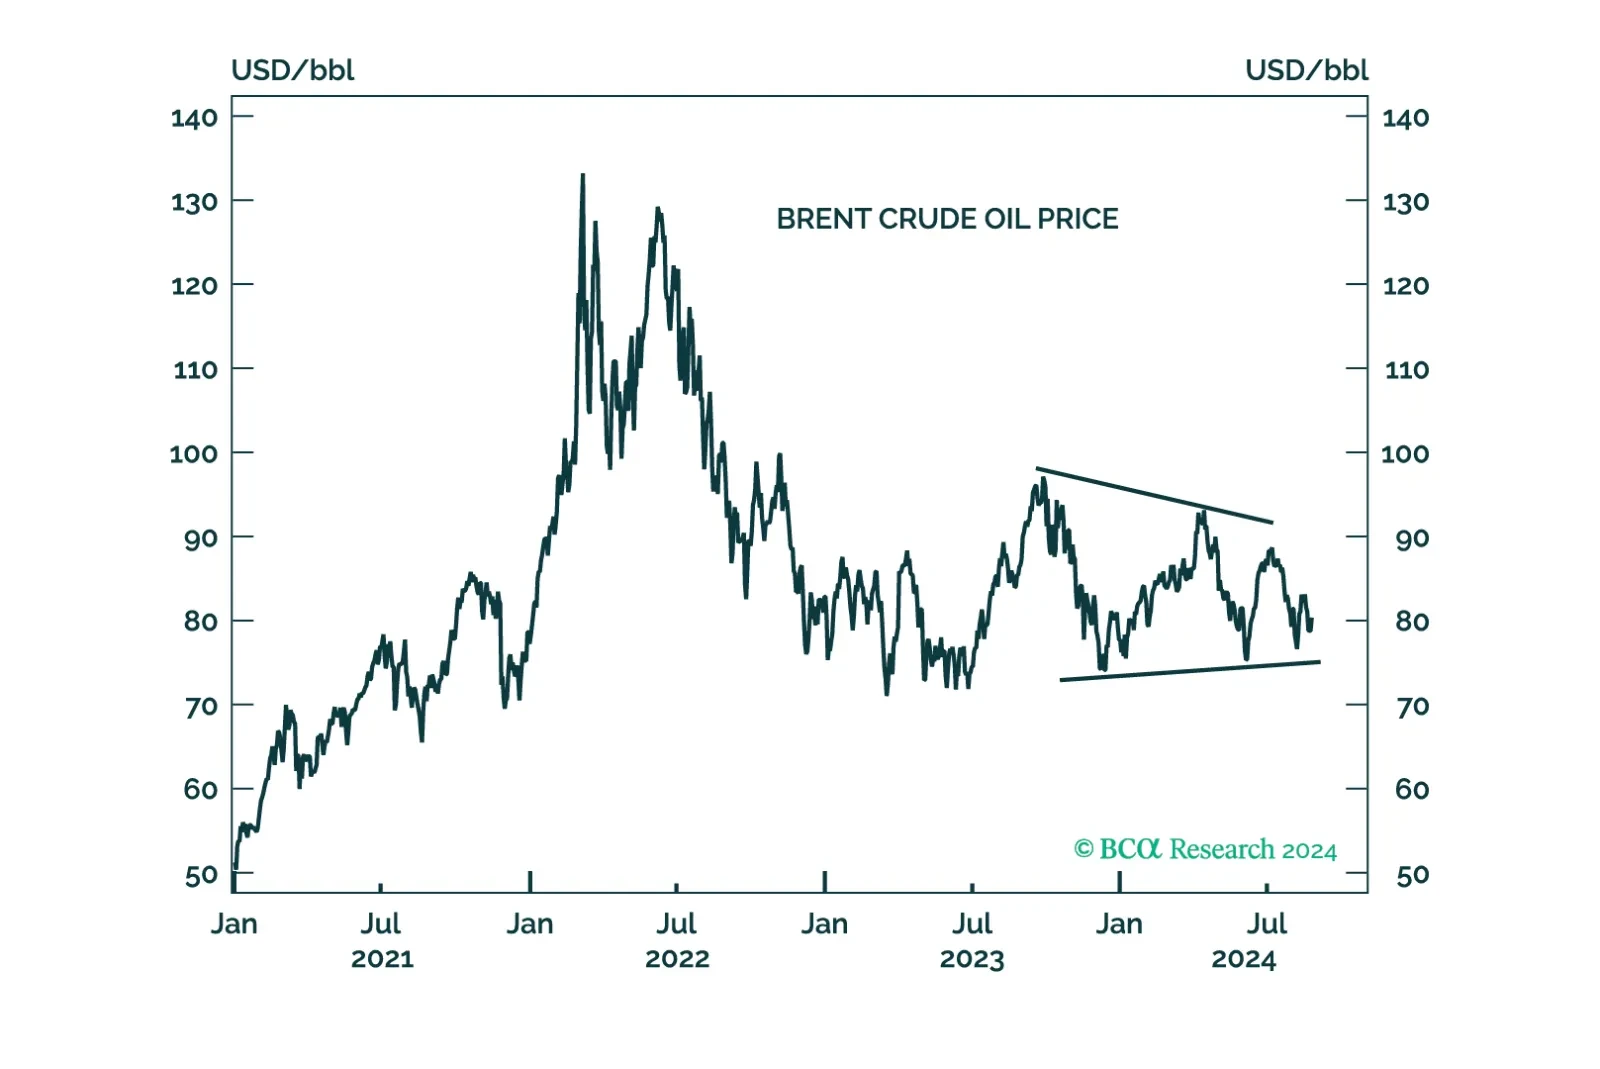
Oil prices failed to hold onto their recent rebound. They slid on Tuesday as demand con-cerns resurfaced. This dynamic is the latest iteration of a tug-of-war that has kept oil prices in a trading range since H2 2023. Bearish demand concerns are enforcing an upper limit on the price of crude while bullish supply risks are maintaining a floor.
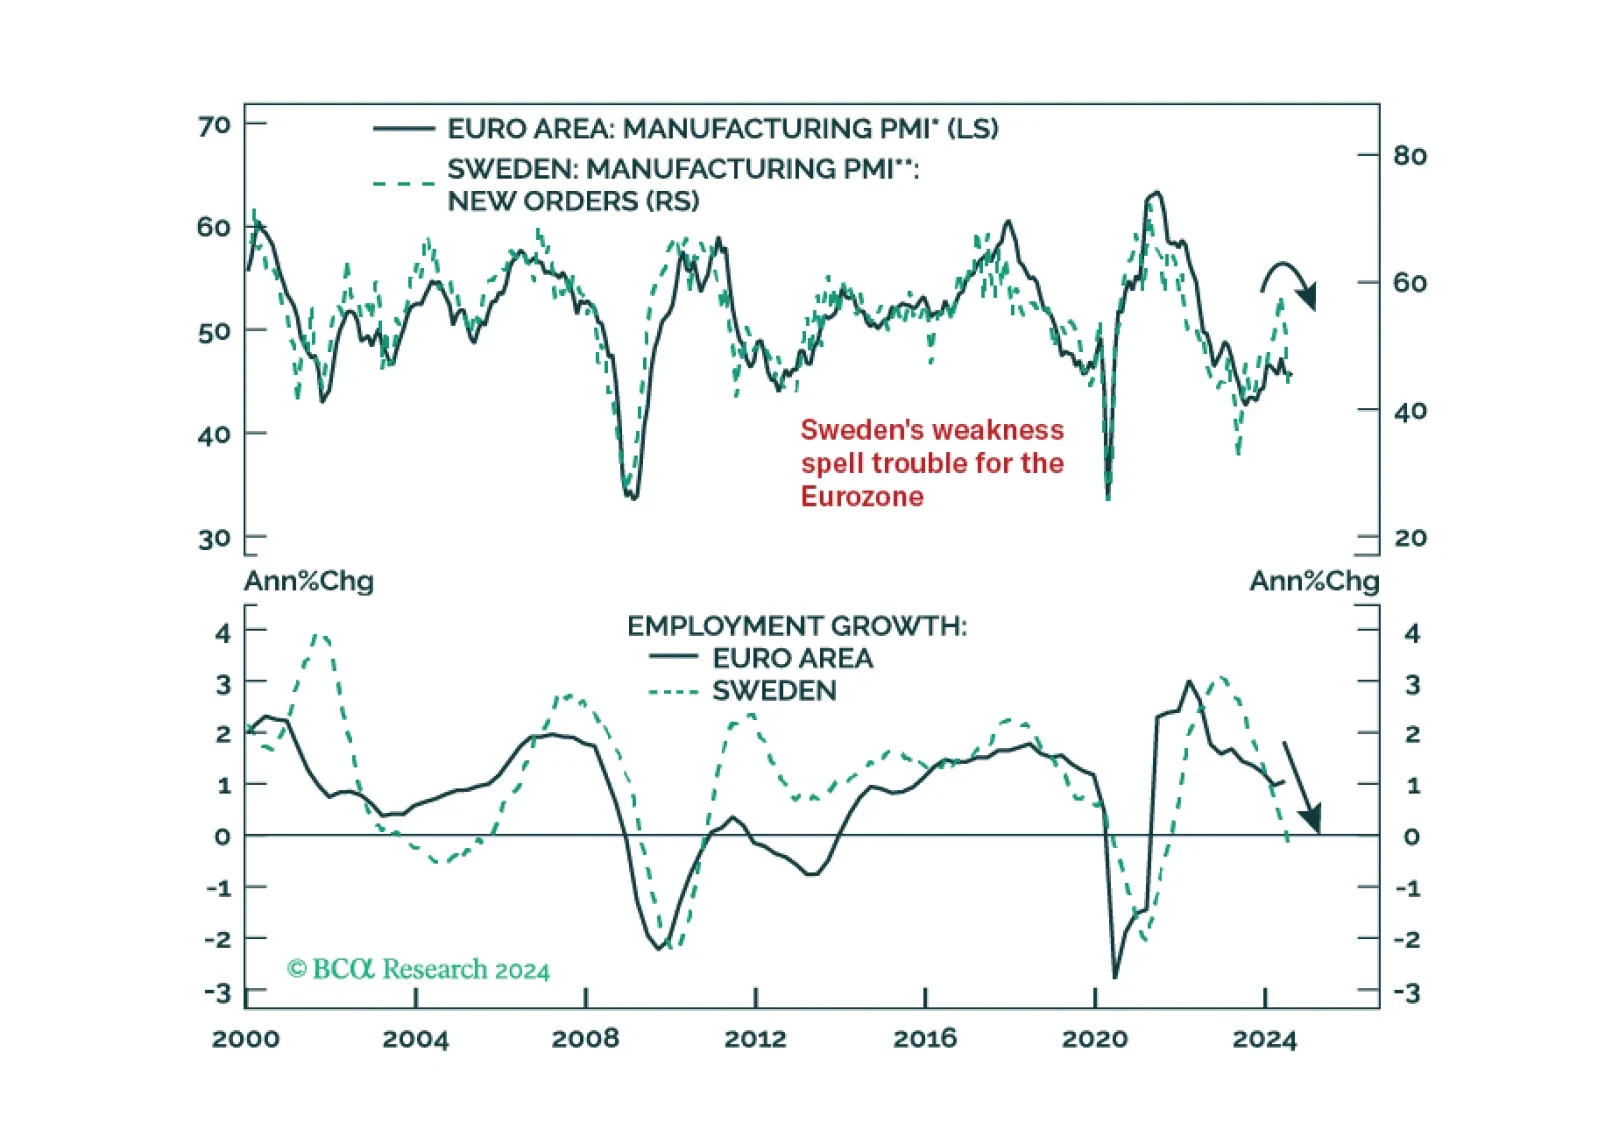
Our negative stance on European growth and assets is not devoid of risks. To gauge whether these risks warrant upgrading our growth outlook, we monitor Sweden closely. So, what is the current message from this Nordic economy?
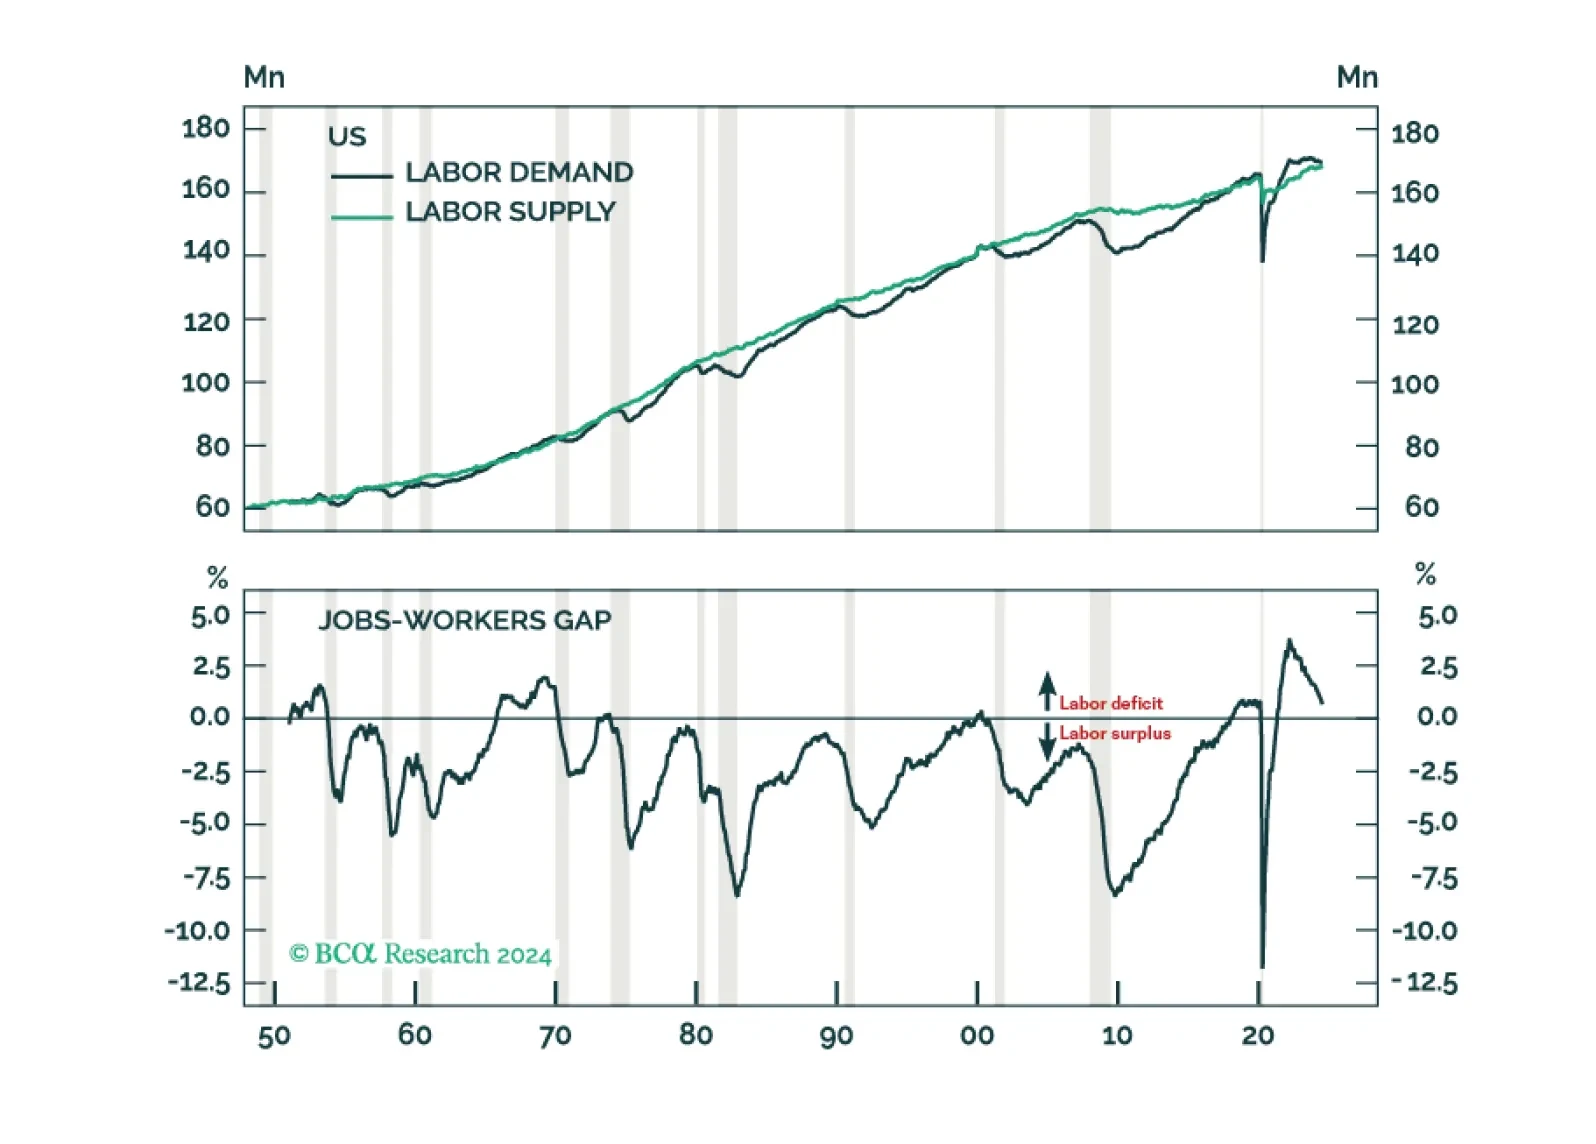
The great US labor market shortage is over. Labor demand will likely fall short of supply by the end of this year, causing unemployment to soar. Neither fiscal nor monetary policy will be able to prevent the coming recession. Investors should underweight stocks and overweight Treasuries.

Private Equity Secondaries have grown but so have their opportunities. Near-term opportunities will be fertile while underlying trends will sustain the asset class in the long-term. Private Equity investors should be greedy.
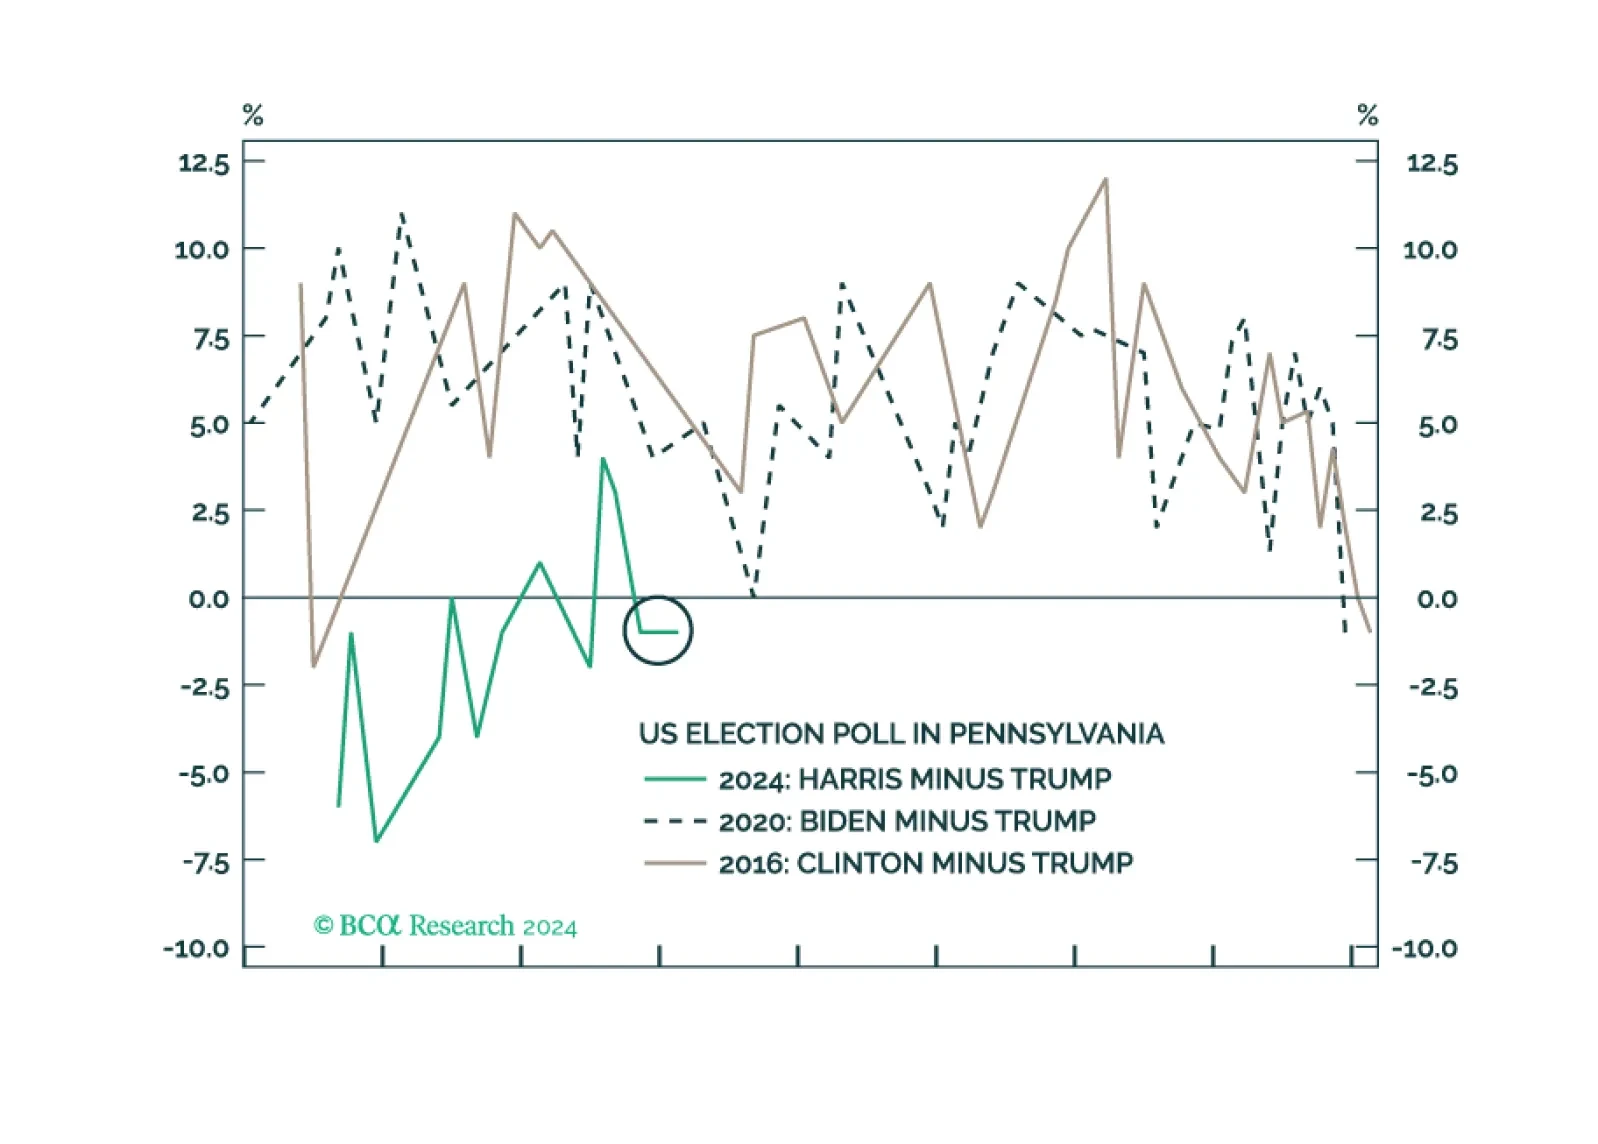
Investors should buy protection against further volatility. The shakeup in early August was a taste of things to come. The US election is a pivotal moment in modern history that will drive up uncertainty, while other countries take advantage of US division and distraction.