Latest from BCA Research
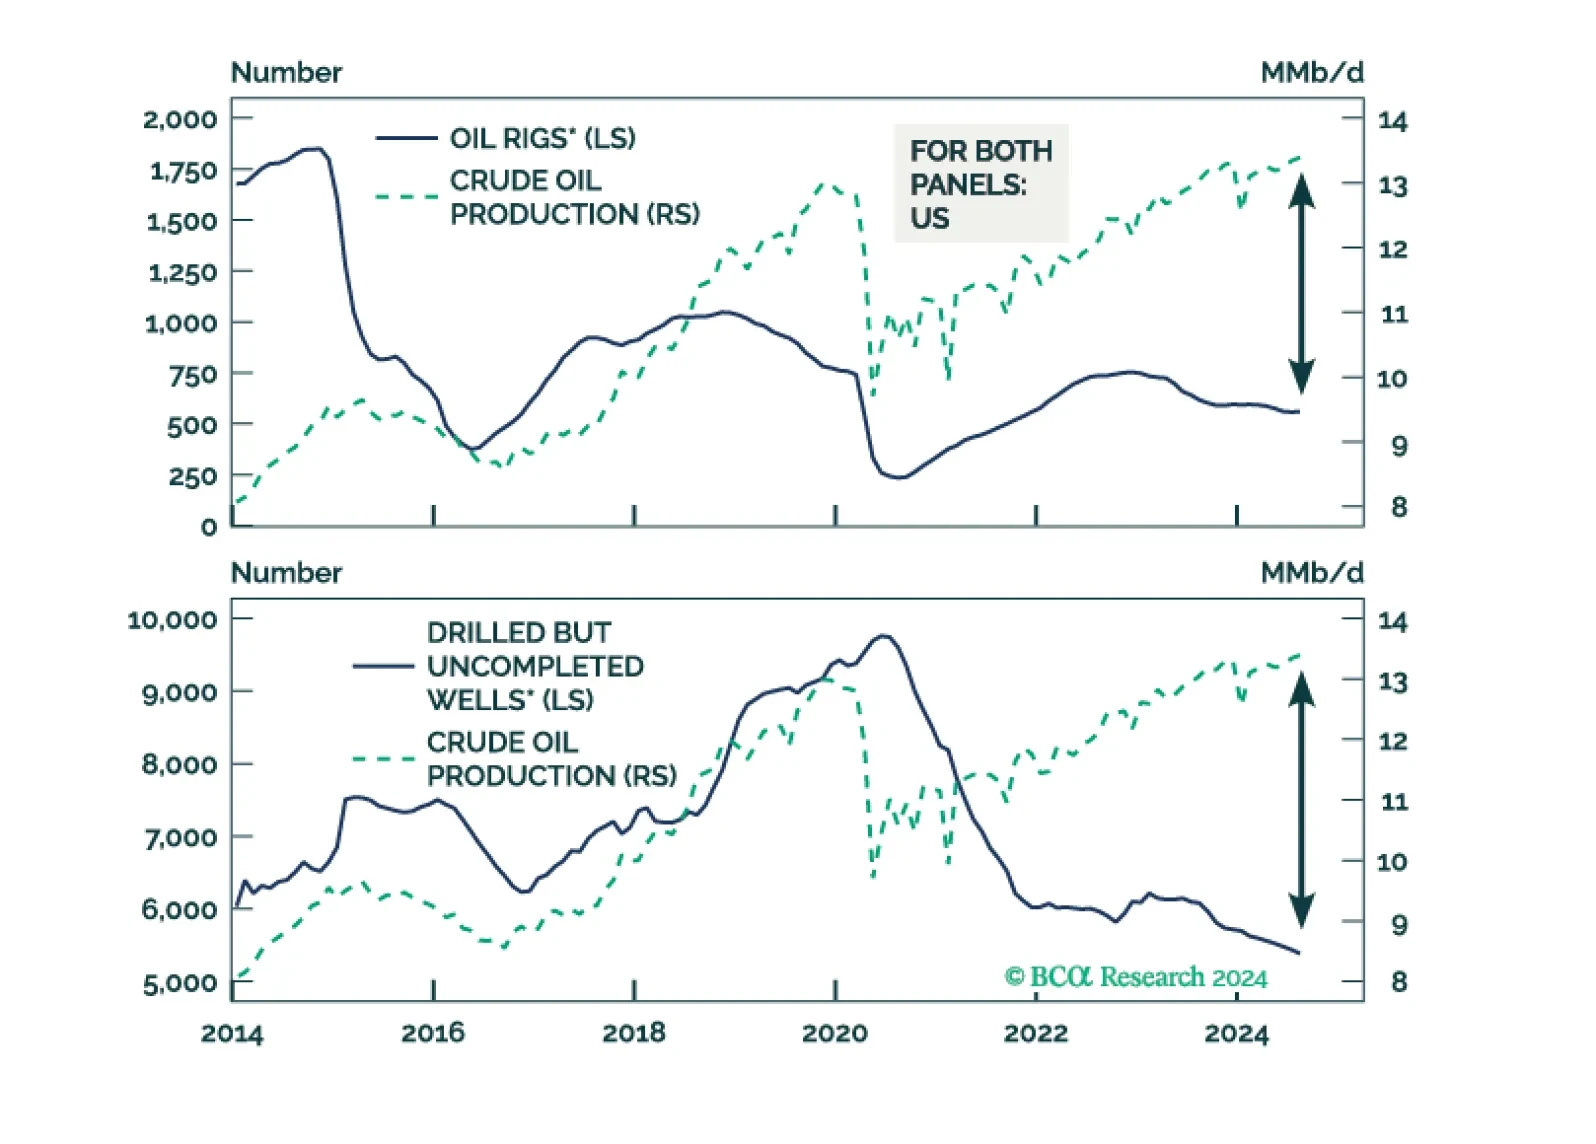
US crude oil output has not peaked. It will continue to increase. A continued expansion of US production, even if it is moderate, along with a possible increase in OPEC+ output, will lead to an oversupplied oil market. Moreover, we expect the demand headwind from the business cycle slowdown to weigh on crude prices. Over a 6-to-12-month horizon, the path of least resistance for oil prices is to the downside.
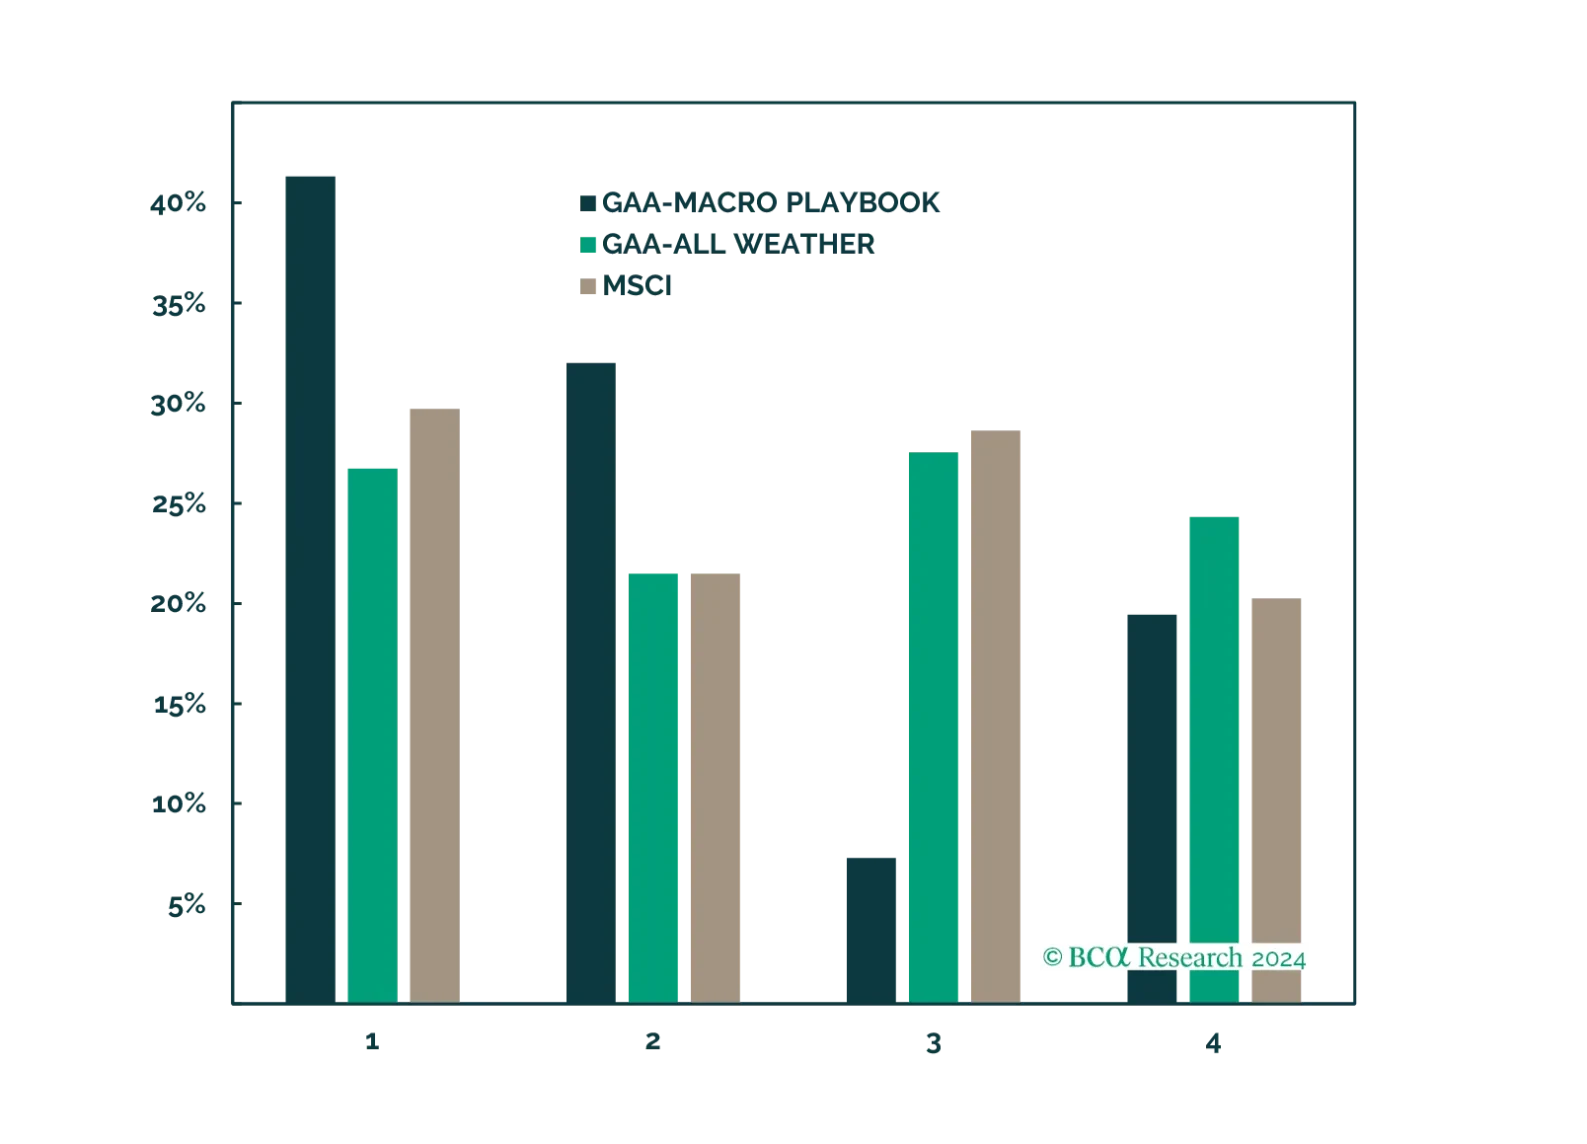
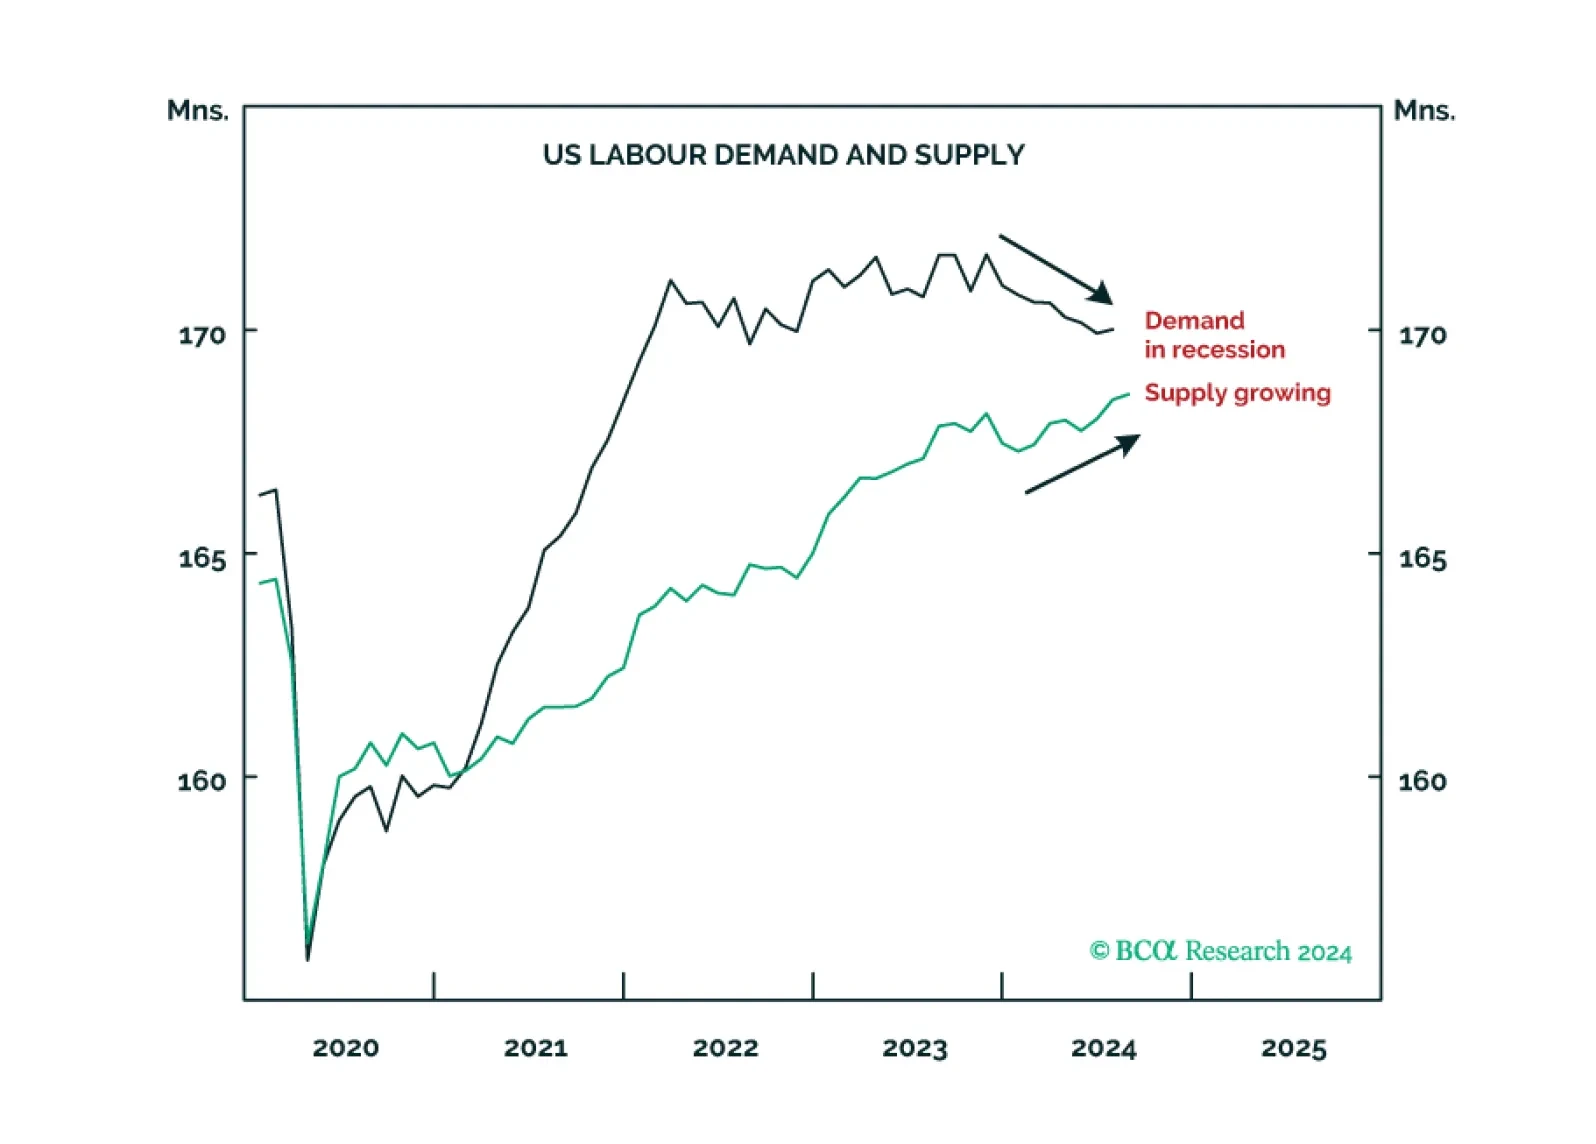
Just like the market for Oasis 2025 reunion tour tickets, the US labour market is ‘supply-constrained’. This means the US will not go into a GDP recession in the next few months and has a good chance of cheating one for longer. Without a GDP recession, there is unlikely to be an economy-wide profits recession. This leads to three recommendation changes on a cyclical (12-month) horizon which we highlight. Plus: the tactical rally in Chinese stocks can continue.
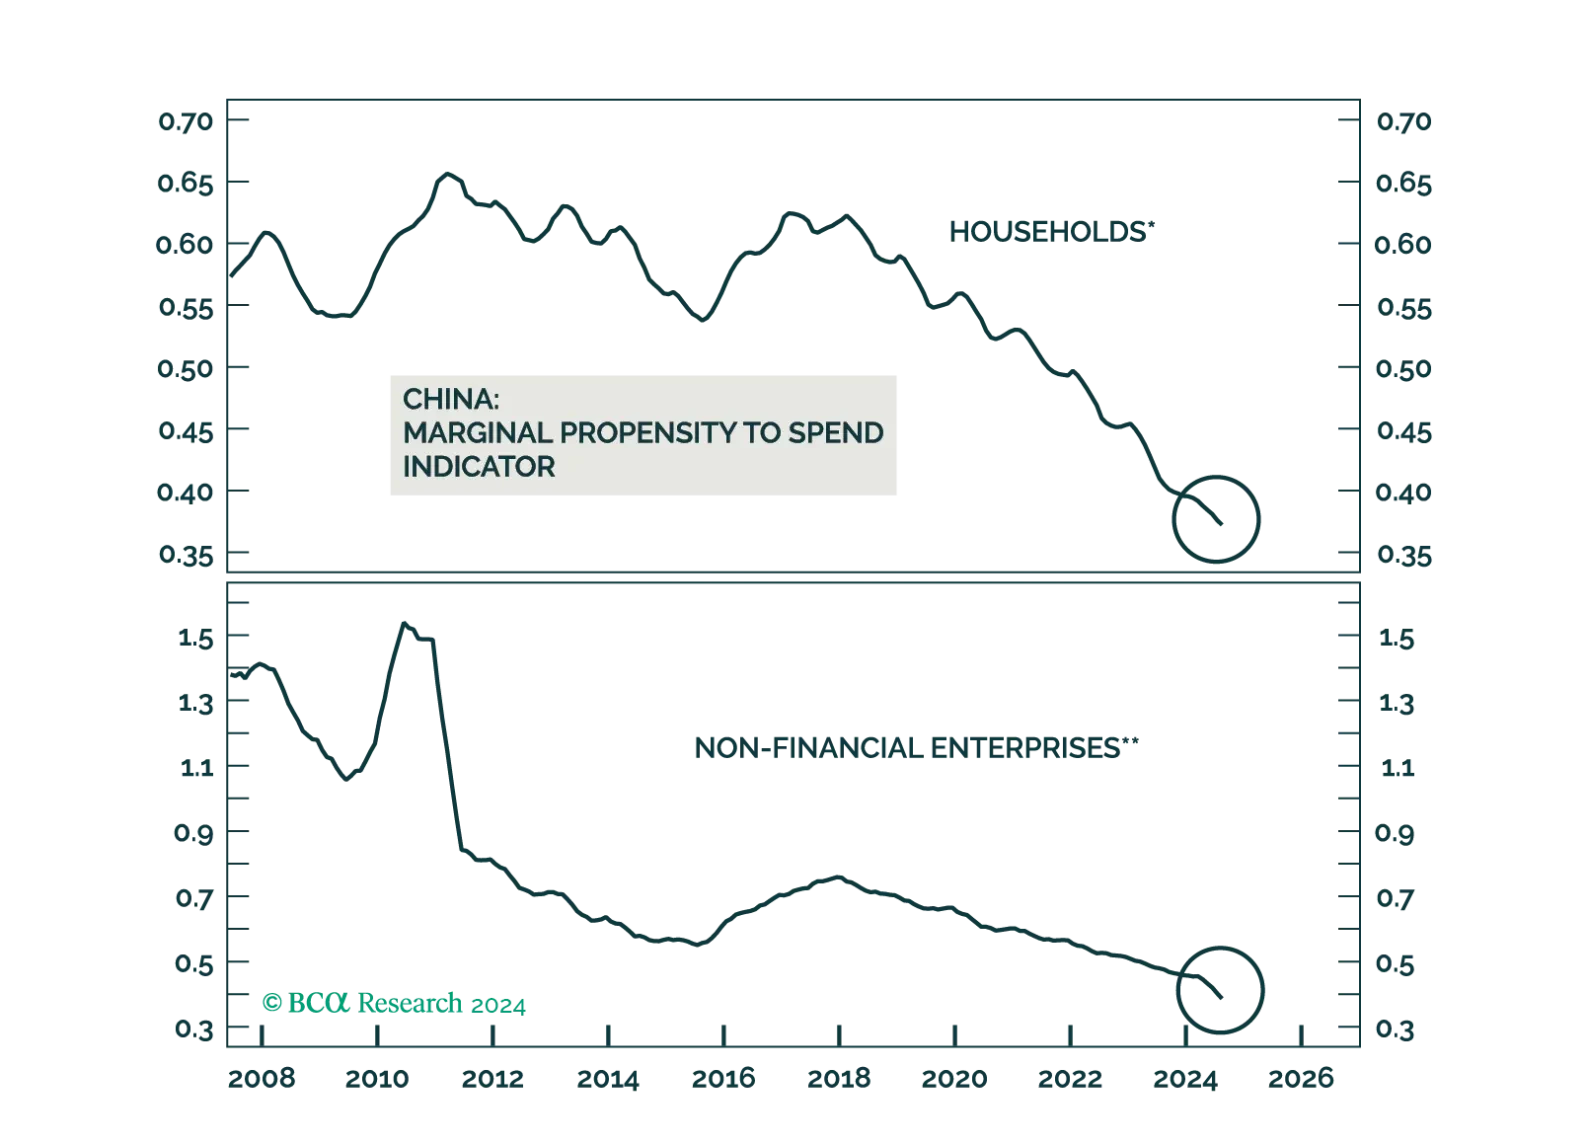
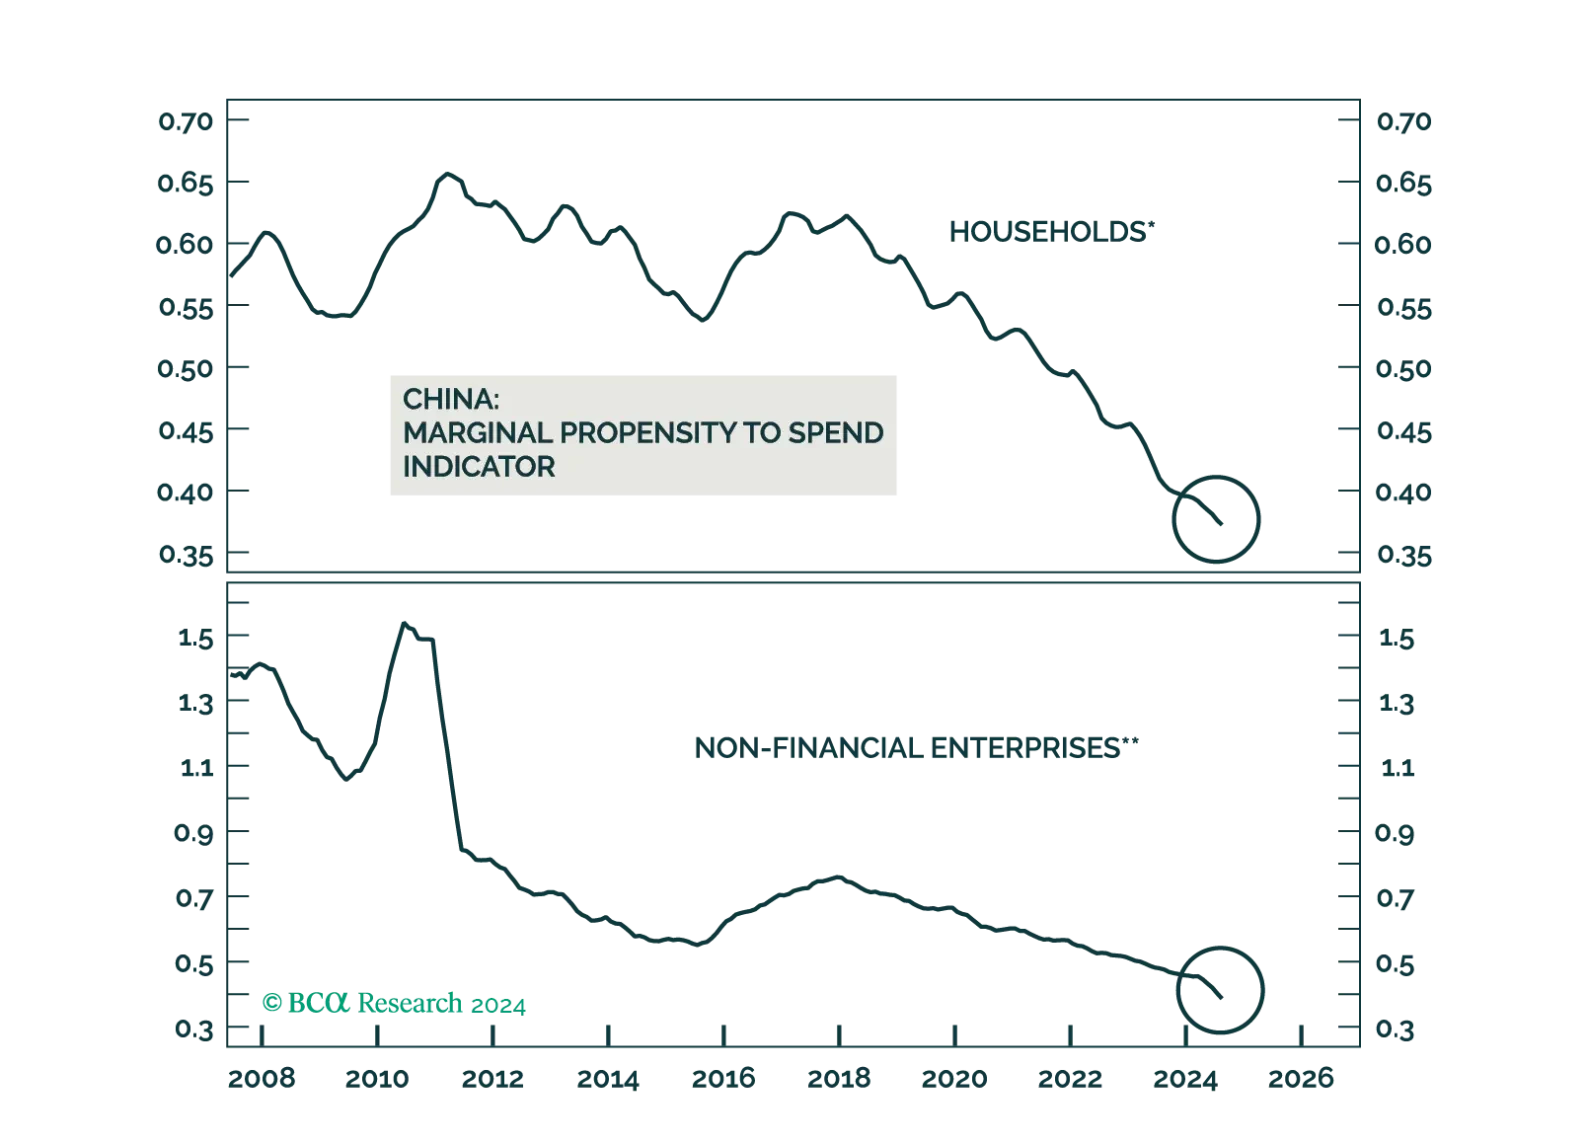
We believe the PBoC’s recent policy stimulus might bolster investor confidence, potentially stabilize onshore Chinese equity prices, and provide modest support to offshore stocks. However, they are unlikely to significantly boost economic growth in the mainland.
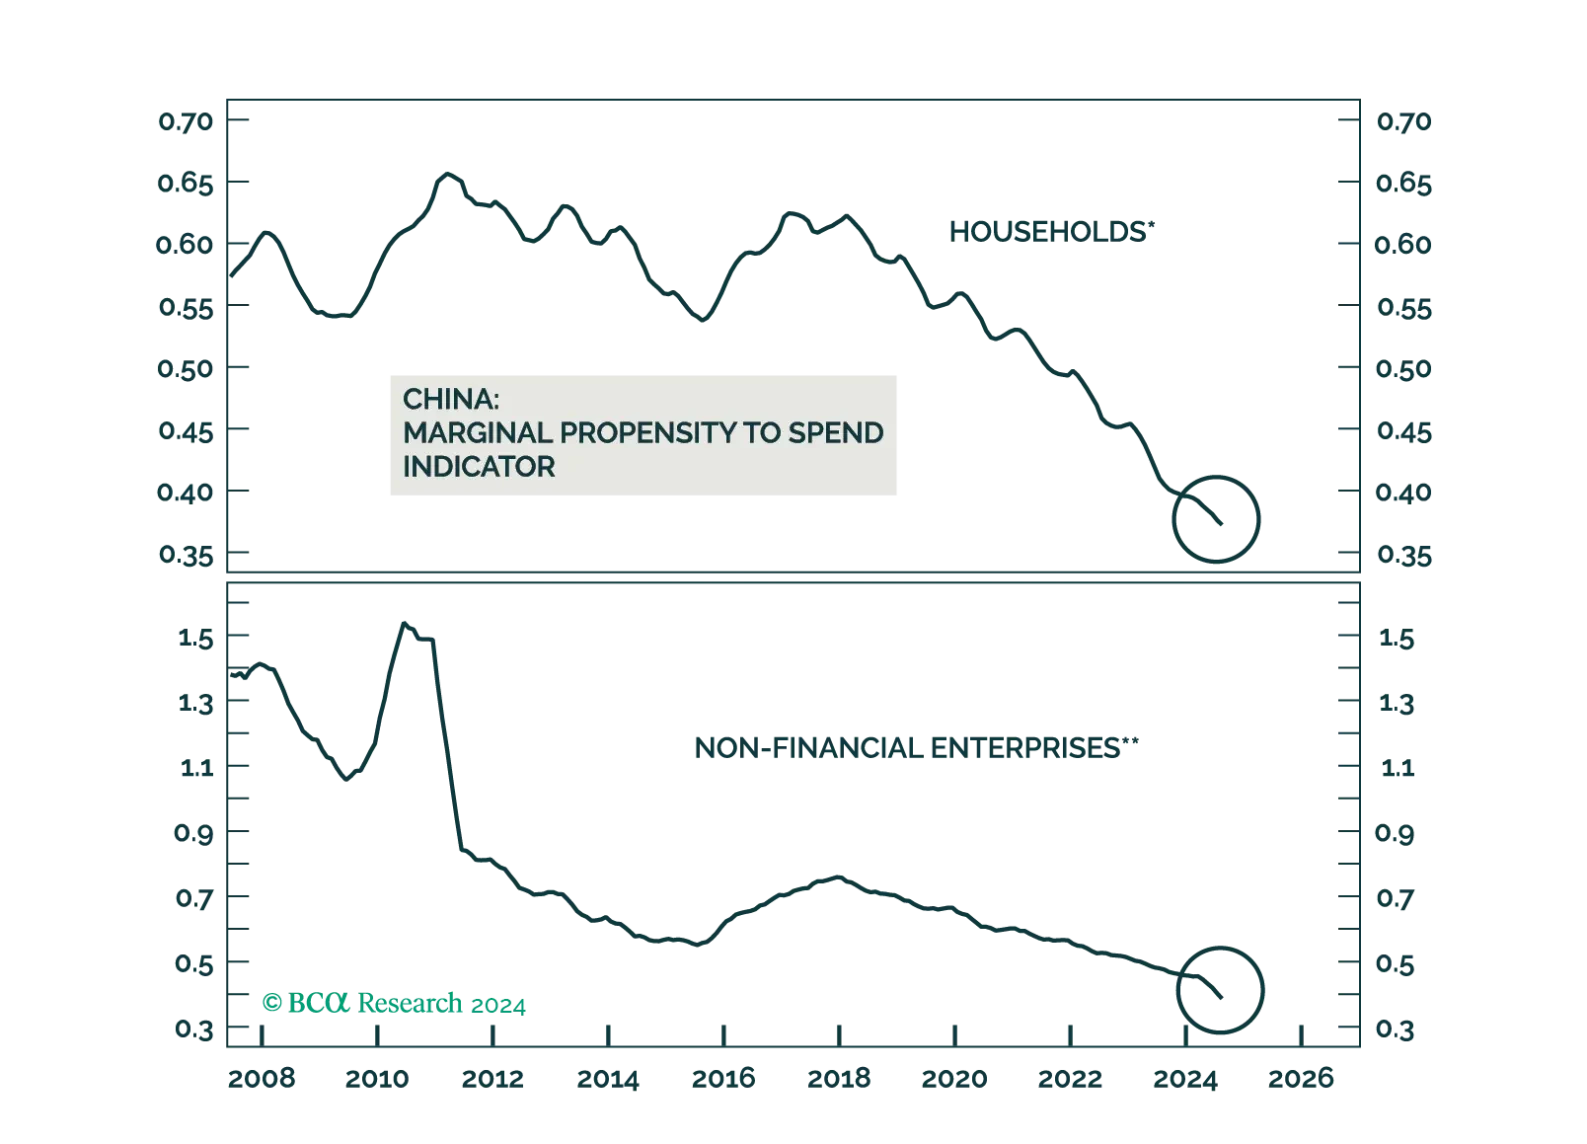
We believe the PBoC’s recent policy stimulus might bolster investor confidence, potentially stabilize onshore Chinese equity prices, and provide modest support to offshore stocks. However, they are unlikely to significantly boost economic growth in the mainland.

This insight parses through the RBA’s latest policy decision, and makes recommendations on whether to expect any rate cuts in 2024, and beyond.
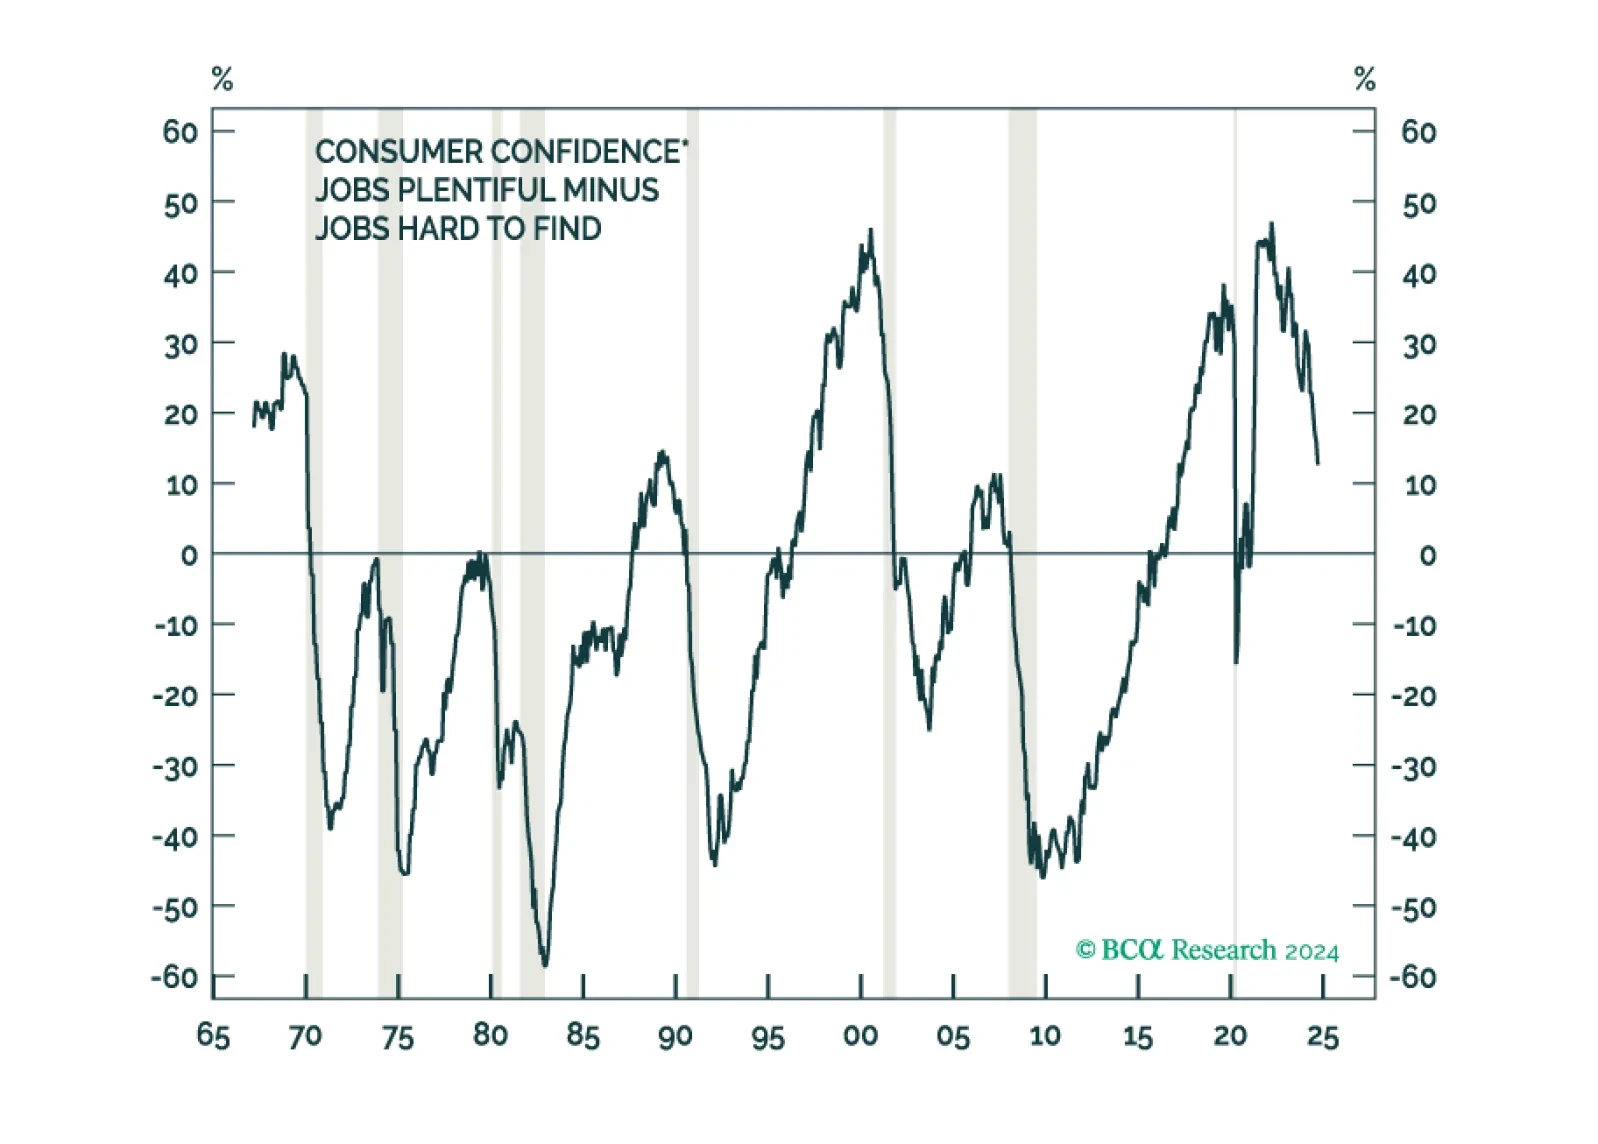
Two days ago, I flagged how the number of people in the US who are working part time but would rather be working full time is rising, which usually only happens in the early stages of recessions.

We update our corporate default rate model and consider the implications for corporate bond spreads.